by Conrad Meertins | Jun 29, 2026 | Uncategorized

If you have spent any time around the appraisal process, you already know that an appraiser and a listing agent look at the same property from two different seats. You are describing a home you know well. I am verifying its characteristics as an independent, impartial third party. The MLS listing is often where those two seats first meet.
After years of appraising homes in the Louisville and Jefferson County area, I can tell you that the information entered into the MLS plays a real role in how smoothly an appraisal assignment goes. This article is not about influencing an outcome. It is about understanding how appraisers actually use listing data, so the data you enter reflects the property accurately.
How an appraiser uses your MLS data

When I receive an assignment, your MLS listing is one of the first things I review. Here is how it factors into the work.
Initial property review. Before I visit, I read the listing to understand what I am being asked to appraise. Square footage, bedroom and bathroom counts, lot size, and listed features all help me plan the inspection and begin identifying comparable sales.
Comparable sales selection. I search recent sales of similar properties to analyze the market. If the listed square footage is off by a few hundred feet, I may begin by considering comparables that are not truly similar. I verify the subject before I rely on those comparisons, but accurate data makes that step cleaner from the start.
Feature verification. During the inspection, I check the details against what is listed. When something differs, USPAP requires me to report the property as I find it. My measured and verified data takes precedence over the listing. That is not a judgment about anyone’s work. It is simply the appraiser’s obligation to report the property accurately.
Market context. Listing data becomes part of the public record that later analysis draws on. Accurate entries contribute to a cleaner data set for everyone who studies the market afterward.
The key point is this: I do not simply accept MLS data as fact. I verify it. When the verified data differs from the listing, the report reflects what I observed and measured.
A common discrepancy, and why it matters

Consider a listing that shows 2,400 square feet and four bedrooms. On inspection, the home measures closer to 2,100 square feet, and the room described as the fourth bedroom is an interior office with no closet and no egress window.
Neither detail is unusual on its own. But when the verified data differs from the listing, the report has to reflect the measured square footage and the actual room count. That can surprise people who were working from the listing figures. The discrepancy is rarely intentional. It usually traces back to an old measurement, a prior listing copied forward, or a room described optimistically. None of that changes the appraiser’s obligation to report the property as it is.
The practical takeaway is simple. The closer the listing is to the verifiable facts of the property, the fewer surprises surface later in the process.
The MLS errors that come up most often

In my experience, these are the listing details most likely to differ from what I measure and verify.
Square footage. This is the big one. Discrepancies of even 100 square feet can matter. Verify total square footage, and be clear about what is included. Finished basement space, for example, is generally analyzed separately from above-grade living area under the ANSI Z765 measuring standard.
Bedroom and bathroom counts. A room generally needs a closet and proper egress to be treated as a bedroom. A half bath without a shower or tub should be noted as a half bath. These distinctions are routine, but they matter to the analysis.
Features and updates. “Recent updates” tells an appraiser very little. Specifics tell us more. “Kitchen renovated in 2025 with new cabinetry, quartz counters, and stainless appliances” is far more useful than “updated kitchen.”
Lot size and dimensions. Incorrect lot information can affect both the analysis and the search for appropriate comparables, especially on larger or unusual lots.
Condition language. “Good condition” means different things to different people. Objective, observable descriptions help. “Original hardwood floors, HVAC replaced in 2023” says more than a single adjective.
Practical habits that keep listings clean

These are the habits I see in agents whose listings consistently hold up well.
Measure carefully. If you are unsure about square footage, measure it or have it measured. The small cost upfront prevents confusion later.
Describe features factually. Note specific, verifiable features of the property. Photos and records of dated improvements help everyone work from the same facts.
Stay objective. If you are not sure whether something qualifies as an upgrade, describe it plainly and let the documentation speak for itself.
Include useful context. Neighborhood details such as proximity to schools or amenities give helpful context, as long as they are accurate.
Update promptly. If something about the property changes before closing, update the MLS. Last-minute differences create unnecessary friction for everyone involved.
Your role in a reliable data set
Every MLS entry becomes part of the record that appraisers, agents, and automated tools draw on later. When the data is accurate, you are contributing to a more reliable picture of the local market and supporting a process that depends on good information.
I do not raise any of this to add a chore to your day. I raise it because accurate data tends to make the whole transaction smoother for everyone at the table. The next time you enter a listing, it can help to remember that an appraiser will use that information while analyzing what is, for most people, their largest financial decision. Measuring carefully, describing features factually, and updating information promptly all support that work.
Accurate MLS data is not a competitive trick. It is simply good, professional practice, and it reflects well on the agent who takes the time to get it right.
by Conrad Meertins | Jun 22, 2026 | Uncategorized

If you are helping an aging parent and their home is part of the picture, you have probably run into questions about Medicaid, estates, and what the property is worth. These situations are stressful, and they tend to mix together legal questions, financial questions, and valuation questions until it is hard to tell which professional handles what. Let me clear up one piece of that: where a real estate appraisal fits, and where it does not.
I want to be straightforward about my role. I am an impartial appraiser. I am not a Medicaid planner or an elder law attorney, and this article is not Medicaid or legal advice. What I can do is explain how a credible, independent opinion of value supports the people who do handle those things.
What an appraisal actually is

An appraisal is an independent, impartial opinion of a property’s market value as of a specific date, developed by a state-licensed or certified appraiser and supported by analysis of the local market. Two features of that definition matter a great deal in estate and Medicaid situations.
First, the appraiser is impartial. The opinion of value is not the family’s number, the attorney’s number, or the buyer’s number. It is an independent conclusion the appraiser can support.
Second, an appraisal is tied to a specific effective date. That is important because these situations often call for a value as of a date in the past, such as a date of death or another date an attorney specifies. Appraisers can perform these retrospective valuations, which is something an online estimate cannot reliably do.
One more point worth knowing, because it trips people up: the exact definition of value depends on why the appraisal is being done. The market value used in a typical lending appraisal is not always the same standard that applies in an estate or tax matter, where a “fair market value” as defined by the IRS or a court may govern. A competent appraiser develops the value under the definition your assignment actually requires, which is one more reason to be specific with your appraiser about the purpose and the advisors involved.
Why families and their advisors often want one

When a parent’s home is involved in Medicaid planning or an estate, the people guiding the family frequently need a documented, defensible value rather than a rough guess. A credible appraisal gives an attorney, a Medicaid planner, or an accountant a clear, supportable figure to work from.
Common reasons a value comes up include settling an estate, supporting tax filings, documenting an arm’s-length sale, or providing records when a benefits program asks for the value of an asset. In each case, the appraiser’s job is the same: provide an accurate, well-supported opinion of value as of the relevant date. How that value is then used is up to the family and their professional advisors.
Where the appraiser’s lane ends
This is the part the internet tends to blur, so let me be clear about it.
Medicaid eligibility, asset and income limits, the look-back period, and estate recovery are legal and benefits questions. They are set at the state level, they are updated periodically, and they vary in ways that genuinely matter. A rule of thumb you read about one state may not apply in Kentucky, and a figure that was current a couple of years ago may have changed.
Because of that, I do not advise on Medicaid eligibility or strategy, and I would be cautious about any source that hands out flat, one-size-fits-all rules on it. For those questions, the right people are a qualified elder law attorney or a Medicaid planner who can look at the specific situation and the current rules in your state. An appraiser supports that work with a value. We do not determine eligibility or how a value will be treated.
Practical steps for adult children and their advisors

If you are working through one of these situations, here is how the appraisal piece fits in cleanly:
- Engage a qualified appraiser for an independent value. Ask for the effective date you actually need, whether that is current or a retrospective date an attorney has specified.
- Bring the appraisal to your legal and financial advisors. They can tell you how the value applies to eligibility, the estate, or taxes. That interpretation is their role, not the appraiser’s.
- Confirm the current rules for your state. Medicaid look-back, asset limits, and estate-recovery rules change and vary by state. Verify them with the Kentucky Medicaid agency or an elder law attorney rather than relying on a general article.
- Keep good records. Documentation of the property’s condition and the basis for its value gives your advisors accurate, factual information to work with.
A final thought
Caring for an aging parent is hard enough without professionals talking past each other. The cleanest way through is to keep the roles distinct. Let an elder law attorney or Medicaid planner handle eligibility and legal strategy, let your accountant handle the tax questions, and let an impartial appraiser handle the one question that is squarely ours: what is this property worth, as of the date that matters, and can that value be supported.
Get those roles in the right lanes, and a complicated situation gets a good deal calmer. And as always, when the rules are involved, it is worth confirming what is current for your state.
by Conrad Meertins | Jun 15, 2026 | Uncategorized

If you are planning to sell your home or refinance your mortgage, you may run into a valuation process that looks different from what you remember. Over the past few years, and most recently in 2025, Fannie Mae has updated how a property’s value can be confirmed on the loans it backs. As an appraiser, my goal here is not to tell you what your home is worth or how to influence that number. It is to help you understand what these changes are and what to expect, so the process feels less like a black box.
Let me walk through it the way I would explain it to a homeowner sitting across my desk.
What actually changed
The headline change is mostly about language and process, and it is worth understanding because the old terms are now out of date.
As of September 3, 2025, Fannie Mae retired the term appraisal waiver. It now uses value acceptance instead. The new term is meant to describe the process more accurately. Rather than “waiving” an appraisal that was assumed to be required, Fannie Mae is accepting a lender-submitted value when its data and modeling support doing so for an eligible transaction. If you hear an older reference to an “appraisal waiver,” understand that people are usually describing what is now called value acceptance.
Fannie Mae also continues to use technology and property data to decide, on a loan-by-loan basis, which valuation path a transaction qualifies for. The eligibility is determined through the lender’s automated underwriting, not by the homeowner.
The valuation paths, in plain terms

It helps to think of these as a range of options, from no appraisal to a full traditional appraisal.
Value acceptance. For certain eligible transactions, Fannie Mae accepts the lender-submitted value with no appraisal required. This relies on data and modeling rather than a visit to the property. In the first quarter of 2025, the eligible loan-to-value ratios for value acceptance on primary residence and second-home purchases increased from 80 percent to 90 percent, which means more transactions can qualify than before.
Value acceptance plus property data. Here there is no traditional appraisal, but a trained third-party data collector visits the property to document the interior and exterior. That information is submitted to Fannie Mae in a standardized format. The collector gathers facts about the property; they are not developing an opinion of value.
Desktop, hybrid, and traditional appraisals. When an appraisal is part of the transaction, it can take one of three forms. A traditional appraisal involves an appraiser inspecting the property in the usual way. A desktop appraisal is completed using property data and records rather than a personal inspection. A hybrid appraisal separates the property visit, often done by a third-party collector, from the appraiser’s analysis. In each case, the appraiser develops an independent, impartial opinion of value.
What this can mean if you are selling or refinancing

Different transactions travel different paths, and which path applies is decided by the lender’s underwriting, not by you or your agent. That is worth knowing so you are not surprised by the process.
If your transaction qualifies for value acceptance, you may not have an appraiser visit the home at all. If it qualifies for value acceptance plus property data, you may have a data collector schedule a visit to document the property, even though no traditional appraisal is being performed. And if a desktop, hybrid, or traditional appraisal is ordered, the timeline and the type of visit will vary accordingly.
For a refinance, the path you qualify for can depend on factors like your loan-to-value ratio and the data available for your property. Higher-equity, lower-risk situations are more likely to be eligible for value acceptance, while other situations may call for an appraisal. None of this is something to game. It is simply helpful to understand which path you are on so you know what to expect and when.
What homeowners can reasonably do

This is the part where it is easy to get the wrong idea, so let me be clear about the appraiser’s role. An appraiser is an impartial third party. The opinion of value comes from an independent analysis of the market, not from anything a homeowner says or wants. My job is to be accurate, not to advocate for a buyer, a seller, or a number.
With that in mind, the most useful thing a homeowner can do is support an accurate process rather than try to influence an outcome:
- Keep good records. If you have completed improvements or upgrades, having documentation of what was done and when, including permits where applicable, gives an appraiser or data collector accurate, factual information to work from.
- Provide access. If a property visit is part of your transaction, making the home available and accessible helps the process move smoothly.
- Ask which path applies. Your lender can tell you whether your transaction is using value acceptance, value acceptance plus property data, or an appraisal. Knowing this sets accurate expectations.
- Understand the difference between facts and opinions. Sharing factual information about your property is appropriate. The conclusion of value remains the appraiser’s independent judgment.
It is reasonable to ask how the value was reached

Here is one piece of encouragement that I think matters. If your transaction qualifies for value acceptance and you are asked to move forward without a traditional appraisal, it is completely reasonable to ask questions before you agree. You can ask your lender which valuation method is being used, how the value was determined, and what data supports it. You are entitled to understand the basis for a number your loan relies on.
This is not about second-guessing the bank. It is about making an informed decision you feel good about. If the explanation gives you confidence in the value, that is reassuring, and you can proceed knowing what is behind it. If you would feel more comfortable with an appraiser’s independent opinion of value, you can ask your lender about your options, including whether a traditional appraisal is available to you. Either way, you are making the choice with your eyes open rather than simply taking the result on faith.
A final thought
Fannie Mae’s recent changes are less dramatic than the headlines sometimes suggest. For the most part, they reflect a shift toward using data and technology to decide how a property’s value gets confirmed, along with clearer language to describe it. For a homeowner, the practical takeaway is simple. Understand which valuation path your transaction is on, keep accurate records of your property, and recognize that the value itself is an independent, impartial conclusion.
The more you understand how the pieces fit together, the calmer the process tends to feel. And as with most things in real estate, there is always a little more to learn as the guidelines continue to evolve.
by Conrad Meertins | Nov 3, 2025 | Uncategorized
You priced the listing based on solid comps. It showed well. You got an accepted offer. Then the appraisal came back short—and suddenly you’re managing a renegotiation, an angry seller, or a dead deal.
Sound familiar?
Here’s what most agents miss: your CMA and the appraiser’s analysis are based on different tools and standards. You’re both analyzing the market — but the appraiser’s opinion of value is based primarily on closed sales and adjustments supported by market data.
The gap between those two perspectives is where deals fall apart. After reviewing thousands of appraisals, I’ve identified the five blind spots that create that gap most often—and how to anticipate them before your next listing goes live.
Table of Contents
- Think Like an Appraiser: The Game Plan
- Blind Spot #1: Ignoring Functional Obsolescence
- Blind Spot #2: Overvaluing Cosmetic Upgrades
- Blind Spot #3: Misreading Market Movement
- Blind Spot #4: Ignoring Micro-Location Premiums
- Blind Spot #5: Not Partnering Early with an Appraiser
The Game Plan: Think Like an Appraiser
Appraisers don’t define “comparable” the way agents do. And that gap is where most pricing mistakes happen.
Here’s what agents often miss: appraisers weight factors based on what the market proves matters—not what agents assume matters. In some markets, square footage drives value. In others, views or condition dominate. The key: it’s always data-driven, never formulaic.
Most CMAs rely on recent sales and general proximity. Appraisers dig deeper—analyzing paired sales to quantify specific differences, reviewing buyer behavior patterns, and testing adjustments against actual market reactions.
Example: An agent might use a same-size home 0.5 miles away because it closed at a great price. An appraiser might reject it because it’s across a busy road or in a different school district—and comparable sales data proves buyers pay differently for those location factors.
The result? Your comp supports your price. The appraiser’s comp doesn’t. And your deal is now $40K underwater. Of course, that’s an over-simplification, but you get the idea.
A note on price per square foot: It’s not a value conclusion—it’s a supporting data point. Appraisers use it to test adjustments and spot trends, but never as a standalone indicator of value. A 1,200 sf home at $400/sf isn’t automatically worth more than a 2,400 sf home at $350/sf. Quality, location, and market-specific features determine value—the math just helps verify consistency.
Bottom line: If you’re not thinking about how the market actually reacts to specific property differences, you’re building your CMA on assumptions the appraiser can’t support.
Blind Spot #1: Ignoring Functional Obsolescence
Functional obsolescence is the valuation term for layouts that don’t work for today’s buyers. It’s not about ugly—it’s about inefficiency that the market penalizes.
Real example: A beautifully remodeled 1960s ranch with brand-new finishes appraised $25K lower than expected. Why? The layout featured four small shotgun bedrooms—each accessible only by walking through another—with no true primary suite and a kitchen cut off from the main living areas.
Despite the high-end materials, buyers consistently paid less for that kind of choppy, outdated layout. The closed sales made it clear: Gorgeous materials couldn’t fix a floor plan that comparable sales proved buyers avoided or paid less for.
Here’s the critical part: appraisers adjust for functional obsolescence when market data proves buyers paid less for inefficient layouts—not based on personal preference or design trends. If comparable sales show a measurable difference in price for similar square footage with better flow, the adjustment is supportable. If not, there’s no adjustment.
Walk the home like an appraiser, not a stager. Ask:
- Does the flow match how buyers live today?
- Is the primary suite competitive with other homes in this price range?
- Are there shotgun bedrooms?
- Do comparable sales show a price difference for these layout issues?
If the answer to that last question is yes, price accordingly. Buyers might fall in love anyway—but the appraiser won’t overlook what the market data reveals.
Blind Spot #2: Overvaluing Cosmetic Upgrades
Here’s the nuanced truth about upgrades: not all improvements add the same value, and market reaction varies by what buyers expect vs. what they reward.
Appraisers distinguish between updates that meet baseline expectations and those that create competitive advantages. A new roof or working HVAC system? Buyers expect those to function—they’re not paying premiums for them. But a thoughtfully updated kitchen with new countertops and backsplash? That can actually shift a home’s condition rating and create measurable market preference.
What often adds measurable value (when done well):
- Kitchen and bath updates that modernize dated spaces (countertops, backsplash, fixtures—especially when they transform the overall impression)
- Square footage additions (permitted)
- View premiums (when comparable sales support them)
- ADUs or income-generating features
- Finished basements or bonus spaces (in markets where this matters)
What typically doesn’t add much (buyers just expect it to work):
- New roof (prevents a deduction, rarely adds premium)
- HVAC replacement (maintenance, not value-add)
- Foundation repairs (fixes a problem, doesn’t create advantage)
- Energy efficiency upgrades (solar, high-efficiency systems—market reaction is inconsistent and often doesn’t match cost)
“A new roof doesn’t add $15K in value—it helps avoid a $15K hit from buyers discounting for deferred maintenance. But a refreshed kitchen can actually improve the home’s marketability and shift its competitive position.”
Here’s why kitchen updates can matter more than you’d think: When countertops and backsplash are part of a coordinated update (maybe paired with paint, hardware, and lighting), they can elevate a home from C4 (Average) to C3 (Average/Good) condition in the appraiser’s analysis. That condition rating shift affects which comparable sales are most relevant—and can support a higher value range.
If your seller just spent $50K on a new roof and HVAC, manage expectations: those updates make the home financeable and marketable, but they’re bringing it to baseline—not past it. If they spent $20K smartly updating the kitchen? That has a better chance of moving the value needle, because it changes how buyers (and appraisers) perceive the home’s competitive position.
The key: Appraisers adjust based on market reaction and condition assessment—not renovation cost or Instagram appeal.
Blind Spot #3: Misreading Market Movement
You’re analyzing current market momentum. Appraisers are verifying it with closed data.
When the market’s moving fast, this creates tension. You’re seeing pending offers at $650K. The appraiser is prioritizing closed sales from recent months at $610K. That $40K gap isn’t imaginary—but it needs to be supported with data, not just asserted based on current listings.
Here’s what many agents don’t realize: Appraisers can and do use pending sales and active listings to support market direction—especially in fast-moving markets. The difference is in how they’re analyzed. Pending sales need verification. Active listings show market expectations, not concluded transactions. Both can support time adjustments or market trend analysis when properly documented.
Here’s how to bridge the gap:
- Provide pending sales data with detail (if you have access to accepted offer prices and can verify terms)
- Include active listings to demonstrate where the market is heading (appraisers can use this to support directional trends)
- Supply market trend data (days on market, absorption rates, price movements by neighborhood or property type)
The key: don’t just show the appraiser what sold. Show them why the market shifted and provide data that supports the trend.
If you’re pricing in a rising market, document everything. Give the appraiser the market story backed by verifiable data—not just current enthusiasm.
And here’s the bottom line: however strong the market momentum, the appraised value still needs to be supported by at least one recent, closed sale that doesn’t require upward adjustment to reach the contract price. Pending and active listings can support a trend—but they can’t carry the value on their own.
Blind Spot #4: Ignoring Micro-Location Premiums
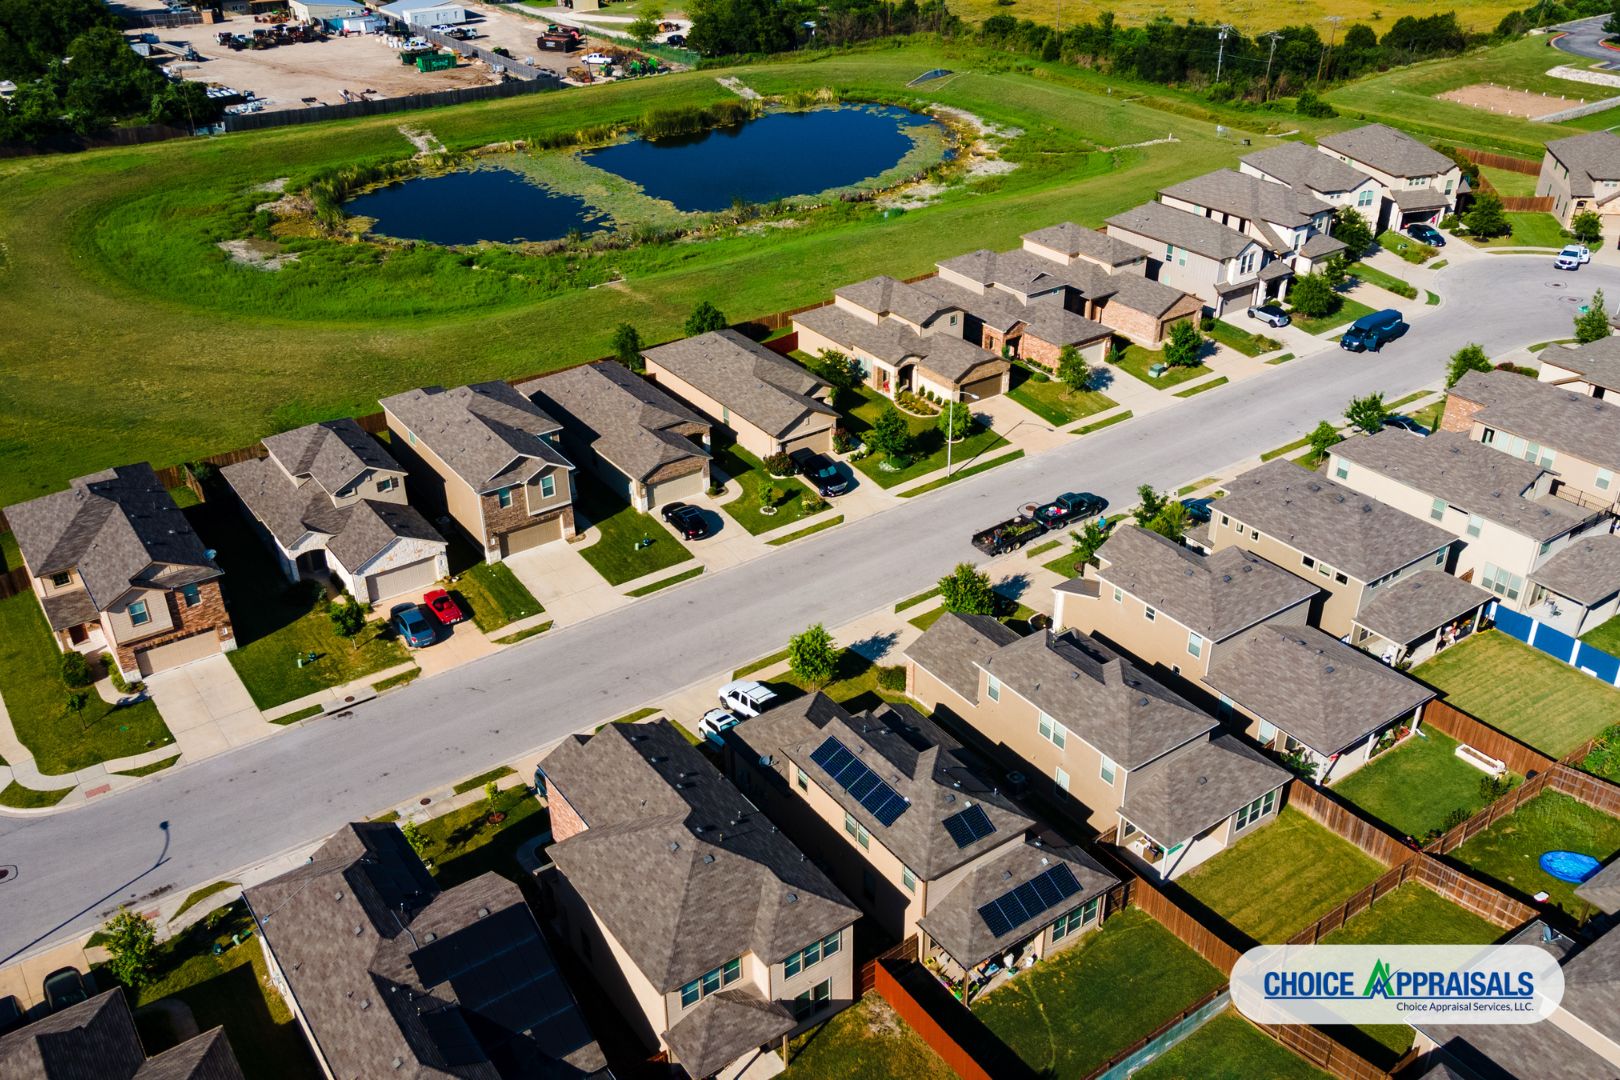
Two identical homes. Same square footage, same finishes, same school district. One backs open space. One backs a retail center parking lot.
The difference? $15,000.
Appraisers analyze micro-location factors that many agents treat as “intangibles”:
- View (mountains, water, open space vs. rooftops or parking lots)
- Orientation (southern exposure vs. northern)
- Traffic patterns (quiet cul-de-sac vs. busy collector road)
- Adjacent land use (greenbelt vs. power lines, parks vs. commercial)
These factors aren’t ignored—they’re adjusted for when market data supports them. An appraiser won’t add $50K for a view just because it’s desirable. They’ll add it because paired sales analysis or comparable sales prove buyers consistently paid a premium for it.
This is why comparable selection matters so much. If your comparable home backs open space and the subject backs a parking lot, that’s not an equal comparison—and appraisers will adjust for the difference if market data quantifies it.
The move: If your listing has a location advantage, identify comparable sales that prove the premium. If it has a disadvantage, find comparables that reflect the penalty and price accordingly. Don’t assume buyers will pay a premium the market data doesn’t support.
Blind Spot #5: Not Partnering Early with an Appraiser
Most agents call an appraiser after the deal is in trouble. Smart agents consult before the listing goes live.
A pre-listing valuation consultation gives you:
- Insight into potential valuation challenges before you commit to a price
- A clearer understanding of which upgrades or features the market actually rewards
- Protection against deal fallout later (you’ve already stress-tested the price against appraisal standards)
Important distinction: This isn’t a formal appraisal—it’s a consulting conversation. No value opinion is provided without a proper appraisal engagement. But the perspective can help you identify red flags early: functional issues the market penalizes, cosmetic upgrades that won’t move the needle, or comparable sales you might have missed.
Think of it as pricing insurance. You’re not guessing what the appraiser will conclude—you’re thinking through the valuation lens before you go live.
Here’s the move: Before your next listing appointment, walk the property with an appraiser’s perspective. Identify the functional issues, the upgrades that matter vs. those that don’t, the micro-location factors that create premiums or penalties. Then price based on what market data will support—not just what current buyer excitement suggests.
And if you’re not sure? Consult with an appraiser before you commit to a number.
Schedule a Pre-Listing Valuation Consultation →
(This is a consulting service—not a formal appraisal. It’s designed to help you identify potential valuation challenges before your listing goes live.)
The Bottom Line
Appraisers don’t kill deals. Unsupportable pricing does.
When you price with the valuation lens—understanding how appraisers analyze comparables, weight market data, and test assumptions—you’re not guessing. You’re building a price that can survive scrutiny.
The agents who master this? They’re the ones sellers trust, buyers respect, and other agents refer to. Because when the appraisal comes back, their deals close.
Next time you price a listing, ask yourself:
Can I support this number with market data an appraiser would find credible?
If you can’t back it up with data an appraiser would find credible, think twice before committing to the price.
by Conrad Meertins | Aug 4, 2025 | Uncategorized
Have you ever wondered how much a spacious backyard or a recently renovated kitchen adds to a property’s value? While only a licensed appraiser can determine a property’s appraised value, understanding how size and condition influence the process can help real estate agents guide clients—and help homeowners make informed decisions about improvements.
This article offers insight into the appraiser’s approach to these key valuation factors, so you can better anticipate what to expect during the appraisal process.
Why Size Matters in Property Valuation
The size of a property is a major factor in determining its value. Appraisers consider how the total gross living area (GLA) compares to similar properties, typically using standards like ANSI Z765 for measurement consistency. Larger homes often have a lower price-per-square-foot due to diminishing returns—each added square foot contributes less to overall value than the one before it.
For example, imagine two homes: one is 1,200 square feet and the other is 2,400. If the smaller home is valued at $300,000, the larger isn’t necessarily worth $600,000. It might be valued at $550,000 because the market doesn’t value extra space at a 1:1 ratio.
What This Means for Agents and Owners: If you’re helping price a home or evaluating renovations, remember that size matters—but how much it matters depends on the local market. Simply adding square footage doesn’t guarantee an equal return in appraised value.
Evaluating Property Condition
Condition is another critical element. Appraisers look at the property’s overall upkeep, including both cosmetic finishes and major systems like roofing, HVAC, plumbing, and electrical. A home in excellent condition with modern updates typically earns a higher market value than a similar home in poor condition.
For instance, energy-efficient windows, a new roof, or a remodeled kitchen can positively influence value—but only if those features align with what buyers in that market are paying more for.
What This Means for Agents and Owners: Updates don’t automatically increase value. Agents should be prepared to discuss condition with sellers in relation to comparable homes in the neighborhood. Homeowners should know that quality upgrades can improve marketability, but appraisers base adjustments on what similar homes have actually sold for.
The Combined Impact of Size and Condition
Appraisers evaluate size and condition together, not in isolation. For example, a large home in poor condition may appraise lower than a smaller home in excellent shape. The context of the local market and buyer demand is key.
Appraisers use techniques like paired sales analysis—comparing similar homes with one key difference—to isolate the value of features like square footage or renovated kitchens. Adjustments aren’t based on set formulas but rather on what the market data supports.
What This Means for Agents and Owners: Agents can better advise clients by understanding that appraisers make value adjustments based on how buyers perceive features in the current market. Homeowners planning upgrades should focus on improvements that are both functional and consistent with neighborhood expectations.
Conclusion
Understanding how appraisers evaluate home size and condition helps demystify a process that can feel opaque. For agents, this knowledge supports better pricing strategies and stronger transactions. For homeowners, it means making informed renovation decisions and having realistic expectations.
Keep in mind: every appraisal is unique, and no single feature guarantees a specific value. The market—not opinion—drives valuation.
Disclaimer: The insights shared in this article are meant to help agents and homeowners understand general appraisal concepts. Only a licensed or certified appraiser can develop or communicate an opinion of value in compliance with the Uniform Standards of Professional Appraisal Practice (USPAP).
by Conrad Meertins | May 5, 2025 | Uncategorized
The world of real estate appraisal can be complex, especially when it comes to understanding adjustments and why cost per square foot (SF) doesn’t always provide an accurate picture. This article aims to shed light on these concepts, with a particular focus on the real estate market in Louisville, KY.
Introduction
Stepping into the world of real estate, you quickly realize it’s not as simple as buying low and selling high. There’s a science, an art if you will, to understanding property values. This is where the concepts of appraisal adjustments and cost per square foot (SF) come into play.
Appraisal adjustments and cost per SF are like the yin and yang of property valuation. They directly impact how much money changes hands in a real estate transaction. Whether you’re a buyer, a seller, an investor, or a real estate professional, understanding these concepts can mean the difference between a successful deal and a costly mistake.
But here’s the kicker: cost per SF, despite its widespread use, doesn’t always paint the full picture. And that’s where appraisal adjustments step in, fine-tuning the value to ensure it reflects the property’s true worth.
The Concept of Appraisal Adjustments
In the realm of real estate, adjustments are the bread and butter of accurate appraisals. Picture this: You’re comparing two houses. Both have the same square footage, the same number of rooms, and they’re in the same neighborhood. But one has a newly renovated kitchen, and the other doesn’t. Does the shiny new kitchen add value? You bet it does. This added value is what we call an “adjustment.”
Adjustments are changes made to the value of a property to account for differences between it and a comparable property. These differences could be anything — from a renovated kitchen to a swimming pool, or even the proximity to a popular school. In essence, adjustments allow appraisers to compare apples to apples when looking at different properties.
Numerous factors can prompt an adjustment — the property’s location, its condition, the size, the number of rooms, and any unique features it may have. The art of making adjustments is a delicate one. It’s not just about assigning value to individual features; it’s about understanding how all these features come together to influence a property’s overall appeal and market value.
Cost per SF: A Common Misconception
Cost per square foot (SF) is calculated by dividing the total cost of a property by its square footage. It’s commonly used because of its simplicity and its ability to provide a quick comparison between different properties. It’s like saying, “Hey, this apple and this orange are both fruits, so let’s compare them based on their weight.” But as we all know, there’s a lot more to properties than just their size.
A critical issue often overlooked is that even within the same neighborhood, cost per SF can be deeply misleading. Realtors frequently cite average cost per SF for a neighborhood as if it’s a uniform standard, but this practice glosses over significant variations between individual properties. Two homes on the same street with identical square footage can legitimately have vastly different values due to lot size, property condition, updates, layout efficiency, and architectural design.
Consider two 2,000 SF homes in Louisville’s Parkway Village neighborhood. One features an efficient floor plan with a modern kitchen, updated bathrooms, and a finished basement. The other has an awkward layout with wasted space, dated fixtures, and foundation issues. Despite sharing the same square footage and neighborhood, these homes should command significantly different prices. Yet cost per SF calculations would suggest they’re equivalent.
When Cost per SF IS Useful
To be fair, cost per SF does have legitimate applications in real estate. It’s particularly valuable in these scenarios:
- New Construction: When builders are estimating costs or pricing similar models in a new development, cost per SF provides a reasonable starting point since construction materials and labor represent a standardized expense.
- Condominiums: In buildings where units have similar finishes, amenities, and views, cost per SF can be more reliable since many variables are controlled.
- Commercial Real Estate: Office buildings, retail spaces, and industrial properties are often valued primarily on their income potential relative to their usable square footage.
- Market Trend Analysis: Looking at average cost per SF changes over time can help identify neighborhood appreciation trends, even if individual properties vary significantly.
- Initial Budget Planning: For buyers establishing a general budget range, neighborhood cost per SF averages can provide a starting reference point.
However, even in these cases, cost per SF should be just one tool among many – not the definitive measure of value.
Why? Cost per SF doesn’t account for the nuances that make each property unique. It overlooks factors such as location, age, condition, design, and the quality of construction, among others. It’s a one-size-fits-all approach in a world where every property is different.
For another example, imagine two properties in Louisville, KY, each with 2,000 SF of space. One is a newly built luxury condo downtown with high-end finishes, while the other is a 30-year-old suburban home needing significant updates. Using cost per SF, these two properties would appear equal. But are they really? Of course not.
That’s the limitation of cost per SF in appraisals. It’s a blunt instrument in a field that requires a scalpel’s precision. It overlooks the nuances that can significantly impact a property’s value, particularly in diverse real estate markets like Louisville, KY.
So, while cost per SF can give you a starting point, it’s just that — a start. To get an accurate appraisal, you need to dig deeper and consider the unique factors that make each property tick.
The Role of Adjustments in Accurate Appraisals
Adjustments are like the fine-tuning knobs on a vintage radio. They help us dial in the right frequency, or in this case, the most accurate property value.
In essence, adjustments account for differences between the subject property and the comparable properties. These differences could range from physical characteristics like the number of bedrooms, age, and size, to location-related aspects like proximity to amenities or quality of schools. Even factors like the condition of the property, or its appeal in the current market trends, can play a role.
Imagine you’re comparing properties in Louisville’s Highlands neighborhood. Your subject property is a charming 2-bedroom bungalow with a no basement, while a comparable property nearby is similar in many ways but features an additional bedroom and a finished basement. In this case, a downward adjustment would be made to the value of the comparable property to account for these differences.
The process of making adjustments is both an art and a science. It requires a combination of market knowledge, analytical skills, and sometimes, a bit of intuition. But when done correctly, adjustments can bring us closer to an accurate appraisal, helping both buyers and sellers make informed decisions.
The Importance of Accurate Appraisals
An inaccurate appraisal can have serious implications. It can skew the perception of a property’s value, leading to either overpricing or underpricing. This can result in a seller losing out on potential profit, or a buyer overpaying for a property. In a worst-case scenario, it can even derail a transaction entirely.
Consider this scenario: you’re selling a historic home in Crescent Hill, and the appraisal comes in significantly lower than your asking price because the appraiser didn’t properly account for the property’s unique architectural features and prime location. The buyer’s mortgage lender isn’t willing to loan more than the appraised value, and the buyer can’t make up the difference. The deal falls through, leaving you back at square one.
Now, let’s flip the script. You’re buying a new construction property in Norton Commons, and the appraisal comes in suspiciously high. Overjoyed at the apparent instant equity, you proceed with the purchase, only to find out later that comparable homes in the area are selling for much less. The feeling of being short-changed is not a pleasant one.
These scenarios underscore the importance of accurate appraisals in the real estate transaction process. They’re not just numbers, but critical tools that help ensure a fair and equitable exchange of properties. They provide a reliable basis for negotiation between buyers and sellers and give lenders the confidence to provide financing.
Conclusion
We’ve journeyed through the intricate world of real estate appraisal, dissecting the often misunderstood concepts of appraisal adjustments and cost per SF.
Remember, cost per SF, while popular, has both uses and limitations. It serves well in specific contexts like new construction, condominiums, commercial real estate, and broad market analysis. However, it falls short when used as the primary valuation tool for individual residential properties, especially when comparing homes within the same neighborhood that have different characteristics, conditions, and features.
It’s especially problematic when realtors and buyers use it to compare dissimilar properties, falsely assuming that similar locations and similar square footage should equate to similar values. The reality is far more complex, with each property possessing unique characteristics that can dramatically affect its true market value.
Appraisal adjustments take these variables into account. They’re the magnifying glass that lets us see the finer details, providing a more accurate appraisal. It’s a complex process, but it’s necessary for fair and equitable real estate transactions.
Whether you’re a seasoned real estate professional or a novice investor, understanding these concepts is vital. It’s like being handed a compass in the middle of the labyrinth — it’ll help you navigate the market with confidence and make informed decisions.
In the end, the goal is to ensure that every real estate transaction is a fair one. And for that, accurate appraisal adjustments are key.
To learn more about the methods I use to ensure accurate appraisals in Louisville KY. Please feel free to reach out to me via email.