by Conrad Meertins | Jun 29, 2026 | Uncategorized

If you have spent any time around the appraisal process, you already know that an appraiser and a listing agent look at the same property from two different seats. You are describing a home you know well. I am verifying its characteristics as an independent, impartial third party. The MLS listing is often where those two seats first meet.
After years of appraising homes in the Louisville and Jefferson County area, I can tell you that the information entered into the MLS plays a real role in how smoothly an appraisal assignment goes. This article is not about influencing an outcome. It is about understanding how appraisers actually use listing data, so the data you enter reflects the property accurately.
How an appraiser uses your MLS data

When I receive an assignment, your MLS listing is one of the first things I review. Here is how it factors into the work.
Initial property review. Before I visit, I read the listing to understand what I am being asked to appraise. Square footage, bedroom and bathroom counts, lot size, and listed features all help me plan the inspection and begin identifying comparable sales.
Comparable sales selection. I search recent sales of similar properties to analyze the market. If the listed square footage is off by a few hundred feet, I may begin by considering comparables that are not truly similar. I verify the subject before I rely on those comparisons, but accurate data makes that step cleaner from the start.
Feature verification. During the inspection, I check the details against what is listed. When something differs, USPAP requires me to report the property as I find it. My measured and verified data takes precedence over the listing. That is not a judgment about anyone’s work. It is simply the appraiser’s obligation to report the property accurately.
Market context. Listing data becomes part of the public record that later analysis draws on. Accurate entries contribute to a cleaner data set for everyone who studies the market afterward.
The key point is this: I do not simply accept MLS data as fact. I verify it. When the verified data differs from the listing, the report reflects what I observed and measured.
A common discrepancy, and why it matters

Consider a listing that shows 2,400 square feet and four bedrooms. On inspection, the home measures closer to 2,100 square feet, and the room described as the fourth bedroom is an interior office with no closet and no egress window.
Neither detail is unusual on its own. But when the verified data differs from the listing, the report has to reflect the measured square footage and the actual room count. That can surprise people who were working from the listing figures. The discrepancy is rarely intentional. It usually traces back to an old measurement, a prior listing copied forward, or a room described optimistically. None of that changes the appraiser’s obligation to report the property as it is.
The practical takeaway is simple. The closer the listing is to the verifiable facts of the property, the fewer surprises surface later in the process.
The MLS errors that come up most often

In my experience, these are the listing details most likely to differ from what I measure and verify.
Square footage. This is the big one. Discrepancies of even 100 square feet can matter. Verify total square footage, and be clear about what is included. Finished basement space, for example, is generally analyzed separately from above-grade living area under the ANSI Z765 measuring standard.
Bedroom and bathroom counts. A room generally needs a closet and proper egress to be treated as a bedroom. A half bath without a shower or tub should be noted as a half bath. These distinctions are routine, but they matter to the analysis.
Features and updates. “Recent updates” tells an appraiser very little. Specifics tell us more. “Kitchen renovated in 2025 with new cabinetry, quartz counters, and stainless appliances” is far more useful than “updated kitchen.”
Lot size and dimensions. Incorrect lot information can affect both the analysis and the search for appropriate comparables, especially on larger or unusual lots.
Condition language. “Good condition” means different things to different people. Objective, observable descriptions help. “Original hardwood floors, HVAC replaced in 2023” says more than a single adjective.
Practical habits that keep listings clean

These are the habits I see in agents whose listings consistently hold up well.
Measure carefully. If you are unsure about square footage, measure it or have it measured. The small cost upfront prevents confusion later.
Describe features factually. Note specific, verifiable features of the property. Photos and records of dated improvements help everyone work from the same facts.
Stay objective. If you are not sure whether something qualifies as an upgrade, describe it plainly and let the documentation speak for itself.
Include useful context. Neighborhood details such as proximity to schools or amenities give helpful context, as long as they are accurate.
Update promptly. If something about the property changes before closing, update the MLS. Last-minute differences create unnecessary friction for everyone involved.
Your role in a reliable data set
Every MLS entry becomes part of the record that appraisers, agents, and automated tools draw on later. When the data is accurate, you are contributing to a more reliable picture of the local market and supporting a process that depends on good information.
I do not raise any of this to add a chore to your day. I raise it because accurate data tends to make the whole transaction smoother for everyone at the table. The next time you enter a listing, it can help to remember that an appraiser will use that information while analyzing what is, for most people, their largest financial decision. Measuring carefully, describing features factually, and updating information promptly all support that work.
Accurate MLS data is not a competitive trick. It is simply good, professional practice, and it reflects well on the agent who takes the time to get it right.
by Conrad Meertins | Jun 10, 2026 | Valuation

Imagine two professionals walking through the same house in the same week. One is on his knees in the crawlspace with a flashlight, testing whether the sump pump kicks on. The other is in the living room with a tape measure and a clipboard, photographing the layout and jotting notes about the floor plan. To the homeowner watching from the kitchen, they look like they are doing the same job. They aren’t. They aren’t even answering the same question.
If you have ever felt fuzzy on where the home inspection ends and the appraisal begins, you are in good company. Buyers, sellers, and even seasoned agents mix these two up all the time. Let me walk you through the difference the way I would explain it to someone sitting across my desk, because understanding it will save you confusion at exactly the moment a transaction gets stressful.
Two different questions
Here is the cleanest way to keep them straight.
A home inspection answers the question: what condition is this house in? An inspector is looking at how the components of the home are functioning, including the roof, the furnace, the wiring, the plumbing, and the foundation, and flagging what is worn, broken, or unsafe.
A home appraisal answers a different question: what is this property worth, and how was that conclusion supported? An appraiser develops an opinion of value based on the market, drawing on comparable sales, the characteristics of the property, and the conditions of the local area, then documents the reasoning in a report.
Condition versus value. That single distinction clears up most of the confusion. The inspector studies the house itself. The appraiser studies how the house sits within its market.
What a home inspection is

A home inspection is a detailed, top-to-bottom examination of the physical condition of a property, usually performed by a licensed home inspector after a purchase contract is signed. The buyer typically orders and pays for it, and it is done for the buyer’s benefit.
The inspector’s job is to find and describe problems. Think of a water heater near the end of its life, a roof with a few years left, a cracked heat exchanger, or evidence of past moisture in the basement. The deliverable is an inspection report, often dozens of pages with photographs, that helps the buyer understand what they are walking into and what may need attention.
What an inspection is not is a statement of what the home is worth. An inspector will not tell you the market value, and a clean inspection does not mean a property will appraise a certain way. They are simply different lenses.
What a home appraisal is

A home appraisal is an independent, impartial opinion of a property’s value, developed by a state-licensed or certified appraiser. In a typical purchase with financing, the lender orders the appraisal, not the buyer or the seller, because the lender needs an objective third party to support the amount being loaned against the property.
That word *impartial* is the heart of it. An appraiser does not work for the buyer or the seller, and is not an advocate for either side. The appraiser’s obligation is to the analysis: to gather relevant data, apply recognized methods, and report a credible, supportable conclusion. Appraisers are bound by the Uniform Standards of Professional Appraisal Practice (USPAP), a set of ethics and performance standards that exist precisely to keep that objectivity intact.
When I measure a home and walk it, I am noting characteristics that influence value, such as size, layout, quality, condition, and how it compares to what else has sold nearby. I observe condition, but through the lens of how the market would respond to it, not as a punch list of repairs. That is a meaningfully different task than an inspection.
Where people get tripped up

A few mix-ups come up again and again, so let me name them directly.
The first one: “the appraiser will tell me everything that is wrong with the house.” That is not their role. An appraiser observes condition as it relates to value and notes items that are readily apparent, but an appraisal is not a substitute for an inspection. If you want a thorough accounting of the home’s working parts, that is what an inspection is for.
The second: “if the inspection looks good, the appraisal will too.” These measure different things. A home can be in excellent condition and still be analyzed against its market like any other property. A clean bill of health from an inspector is about condition, not value.
The third: “they are both just the bank’s box to check.” Each serves a distinct purpose. The inspection protects the buyer’s understanding of the home. The appraisal gives the lender an independent, supported analysis. Different audiences, different questions.
Putting it to work

So how do you use this, practically?
If you are a buyer or seller, remember that these two reports answer different questions, and you generally want both perspectives in a transaction. One helps you understand the home’s condition. The other provides an independent analysis of value for the lender. Do not expect either to do the other’s job.
If you are a real estate agent, this is a place where you can add real value for your clients. When you can explain clearly why the inspection and the appraisal are separate, and set expectations early, you reduce the surprise and friction that tend to surface late in a deal. Clients remember the professional who made the process make sense.
And if you ever find yourself unsure which report addresses your question, come back to the simple test. Am I asking about the condition of the house, or about its value? The answer tells you which professional you need.
A final thought
I have spent years on both sides of the front door, measuring, analyzing, and explaining how value gets supported. What I have learned is that most of the friction in a real estate transaction comes not from the numbers themselves, but from misunderstandings about who does what and why. The appraisal and the inspection are not competitors, and they are not interchangeable. They are two different tools, built to answer two different questions, and a transaction tends to go more smoothly when everyone understands which is which.
The more you understand each professional’s role, the better equipped you are to ask the right questions. And there is always a bit more to learn about how this all fits together.
by Conrad Meertins | Nov 3, 2025 | Uncategorized
You priced the listing based on solid comps. It showed well. You got an accepted offer. Then the appraisal came back short—and suddenly you’re managing a renegotiation, an angry seller, or a dead deal.
Sound familiar?
Here’s what most agents miss: your CMA and the appraiser’s analysis are based on different tools and standards. You’re both analyzing the market — but the appraiser’s opinion of value is based primarily on closed sales and adjustments supported by market data.
The gap between those two perspectives is where deals fall apart. After reviewing thousands of appraisals, I’ve identified the five blind spots that create that gap most often—and how to anticipate them before your next listing goes live.
Table of Contents
- Think Like an Appraiser: The Game Plan
- Blind Spot #1: Ignoring Functional Obsolescence
- Blind Spot #2: Overvaluing Cosmetic Upgrades
- Blind Spot #3: Misreading Market Movement
- Blind Spot #4: Ignoring Micro-Location Premiums
- Blind Spot #5: Not Partnering Early with an Appraiser
The Game Plan: Think Like an Appraiser
Appraisers don’t define “comparable” the way agents do. And that gap is where most pricing mistakes happen.
Here’s what agents often miss: appraisers weight factors based on what the market proves matters—not what agents assume matters. In some markets, square footage drives value. In others, views or condition dominate. The key: it’s always data-driven, never formulaic.
Most CMAs rely on recent sales and general proximity. Appraisers dig deeper—analyzing paired sales to quantify specific differences, reviewing buyer behavior patterns, and testing adjustments against actual market reactions.
Example: An agent might use a same-size home 0.5 miles away because it closed at a great price. An appraiser might reject it because it’s across a busy road or in a different school district—and comparable sales data proves buyers pay differently for those location factors.
The result? Your comp supports your price. The appraiser’s comp doesn’t. And your deal is now $40K underwater. Of course, that’s an over-simplification, but you get the idea.
A note on price per square foot: It’s not a value conclusion—it’s a supporting data point. Appraisers use it to test adjustments and spot trends, but never as a standalone indicator of value. A 1,200 sf home at $400/sf isn’t automatically worth more than a 2,400 sf home at $350/sf. Quality, location, and market-specific features determine value—the math just helps verify consistency.
Bottom line: If you’re not thinking about how the market actually reacts to specific property differences, you’re building your CMA on assumptions the appraiser can’t support.
Blind Spot #1: Ignoring Functional Obsolescence
Functional obsolescence is the valuation term for layouts that don’t work for today’s buyers. It’s not about ugly—it’s about inefficiency that the market penalizes.
Real example: A beautifully remodeled 1960s ranch with brand-new finishes appraised $25K lower than expected. Why? The layout featured four small shotgun bedrooms—each accessible only by walking through another—with no true primary suite and a kitchen cut off from the main living areas.
Despite the high-end materials, buyers consistently paid less for that kind of choppy, outdated layout. The closed sales made it clear: Gorgeous materials couldn’t fix a floor plan that comparable sales proved buyers avoided or paid less for.
Here’s the critical part: appraisers adjust for functional obsolescence when market data proves buyers paid less for inefficient layouts—not based on personal preference or design trends. If comparable sales show a measurable difference in price for similar square footage with better flow, the adjustment is supportable. If not, there’s no adjustment.
Walk the home like an appraiser, not a stager. Ask:
- Does the flow match how buyers live today?
- Is the primary suite competitive with other homes in this price range?
- Are there shotgun bedrooms?
- Do comparable sales show a price difference for these layout issues?
If the answer to that last question is yes, price accordingly. Buyers might fall in love anyway—but the appraiser won’t overlook what the market data reveals.
Blind Spot #2: Overvaluing Cosmetic Upgrades
Here’s the nuanced truth about upgrades: not all improvements add the same value, and market reaction varies by what buyers expect vs. what they reward.
Appraisers distinguish between updates that meet baseline expectations and those that create competitive advantages. A new roof or working HVAC system? Buyers expect those to function—they’re not paying premiums for them. But a thoughtfully updated kitchen with new countertops and backsplash? That can actually shift a home’s condition rating and create measurable market preference.
What often adds measurable value (when done well):
- Kitchen and bath updates that modernize dated spaces (countertops, backsplash, fixtures—especially when they transform the overall impression)
- Square footage additions (permitted)
- View premiums (when comparable sales support them)
- ADUs or income-generating features
- Finished basements or bonus spaces (in markets where this matters)
What typically doesn’t add much (buyers just expect it to work):
- New roof (prevents a deduction, rarely adds premium)
- HVAC replacement (maintenance, not value-add)
- Foundation repairs (fixes a problem, doesn’t create advantage)
- Energy efficiency upgrades (solar, high-efficiency systems—market reaction is inconsistent and often doesn’t match cost)
“A new roof doesn’t add $15K in value—it helps avoid a $15K hit from buyers discounting for deferred maintenance. But a refreshed kitchen can actually improve the home’s marketability and shift its competitive position.”
Here’s why kitchen updates can matter more than you’d think: When countertops and backsplash are part of a coordinated update (maybe paired with paint, hardware, and lighting), they can elevate a home from C4 (Average) to C3 (Average/Good) condition in the appraiser’s analysis. That condition rating shift affects which comparable sales are most relevant—and can support a higher value range.
If your seller just spent $50K on a new roof and HVAC, manage expectations: those updates make the home financeable and marketable, but they’re bringing it to baseline—not past it. If they spent $20K smartly updating the kitchen? That has a better chance of moving the value needle, because it changes how buyers (and appraisers) perceive the home’s competitive position.
The key: Appraisers adjust based on market reaction and condition assessment—not renovation cost or Instagram appeal.
Blind Spot #3: Misreading Market Movement
You’re analyzing current market momentum. Appraisers are verifying it with closed data.
When the market’s moving fast, this creates tension. You’re seeing pending offers at $650K. The appraiser is prioritizing closed sales from recent months at $610K. That $40K gap isn’t imaginary—but it needs to be supported with data, not just asserted based on current listings.
Here’s what many agents don’t realize: Appraisers can and do use pending sales and active listings to support market direction—especially in fast-moving markets. The difference is in how they’re analyzed. Pending sales need verification. Active listings show market expectations, not concluded transactions. Both can support time adjustments or market trend analysis when properly documented.
Here’s how to bridge the gap:
- Provide pending sales data with detail (if you have access to accepted offer prices and can verify terms)
- Include active listings to demonstrate where the market is heading (appraisers can use this to support directional trends)
- Supply market trend data (days on market, absorption rates, price movements by neighborhood or property type)
The key: don’t just show the appraiser what sold. Show them why the market shifted and provide data that supports the trend.
If you’re pricing in a rising market, document everything. Give the appraiser the market story backed by verifiable data—not just current enthusiasm.
And here’s the bottom line: however strong the market momentum, the appraised value still needs to be supported by at least one recent, closed sale that doesn’t require upward adjustment to reach the contract price. Pending and active listings can support a trend—but they can’t carry the value on their own.
Blind Spot #4: Ignoring Micro-Location Premiums
Two identical homes. Same square footage, same finishes, same school district. One backs open space. One backs a retail center parking lot.
The difference? $15,000.
Appraisers analyze micro-location factors that many agents treat as “intangibles”:
- View (mountains, water, open space vs. rooftops or parking lots)
- Orientation (southern exposure vs. northern)
- Traffic patterns (quiet cul-de-sac vs. busy collector road)
- Adjacent land use (greenbelt vs. power lines, parks vs. commercial)
These factors aren’t ignored—they’re adjusted for when market data supports them. An appraiser won’t add $50K for a view just because it’s desirable. They’ll add it because paired sales analysis or comparable sales prove buyers consistently paid a premium for it.
This is why comparable selection matters so much. If your comparable home backs open space and the subject backs a parking lot, that’s not an equal comparison—and appraisers will adjust for the difference if market data quantifies it.
The move: If your listing has a location advantage, identify comparable sales that prove the premium. If it has a disadvantage, find comparables that reflect the penalty and price accordingly. Don’t assume buyers will pay a premium the market data doesn’t support.
Blind Spot #5: Not Partnering Early with an Appraiser
Most agents call an appraiser after the deal is in trouble. Smart agents consult before the listing goes live.
A pre-listing valuation consultation gives you:
- Insight into potential valuation challenges before you commit to a price
- A clearer understanding of which upgrades or features the market actually rewards
- Protection against deal fallout later (you’ve already stress-tested the price against appraisal standards)
Important distinction: This isn’t a formal appraisal—it’s a consulting conversation. No value opinion is provided without a proper appraisal engagement. But the perspective can help you identify red flags early: functional issues the market penalizes, cosmetic upgrades that won’t move the needle, or comparable sales you might have missed.
Think of it as pricing insurance. You’re not guessing what the appraiser will conclude—you’re thinking through the valuation lens before you go live.
Here’s the move: Before your next listing appointment, walk the property with an appraiser’s perspective. Identify the functional issues, the upgrades that matter vs. those that don’t, the micro-location factors that create premiums or penalties. Then price based on what market data will support—not just what current buyer excitement suggests.
And if you’re not sure? Consult with an appraiser before you commit to a number.
Schedule a Pre-Listing Valuation Consultation →
(This is a consulting service—not a formal appraisal. It’s designed to help you identify potential valuation challenges before your listing goes live.)
The Bottom Line
Appraisers don’t kill deals. Unsupportable pricing does.
When you price with the valuation lens—understanding how appraisers analyze comparables, weight market data, and test assumptions—you’re not guessing. You’re building a price that can survive scrutiny.
The agents who master this? They’re the ones sellers trust, buyers respect, and other agents refer to. Because when the appraisal comes back, their deals close.
Next time you price a listing, ask yourself:
Can I support this number with market data an appraiser would find credible?
If you can’t back it up with data an appraiser would find credible, think twice before committing to the price.
by Conrad Meertins | Aug 4, 2025 | Uncategorized
Have you ever wondered how much a spacious backyard or a recently renovated kitchen adds to a property’s value? While only a licensed appraiser can determine a property’s appraised value, understanding how size and condition influence the process can help real estate agents guide clients—and help homeowners make informed decisions about improvements.
This article offers insight into the appraiser’s approach to these key valuation factors, so you can better anticipate what to expect during the appraisal process.
Why Size Matters in Property Valuation
The size of a property is a major factor in determining its value. Appraisers consider how the total gross living area (GLA) compares to similar properties, typically using standards like ANSI Z765 for measurement consistency. Larger homes often have a lower price-per-square-foot due to diminishing returns—each added square foot contributes less to overall value than the one before it.
For example, imagine two homes: one is 1,200 square feet and the other is 2,400. If the smaller home is valued at $300,000, the larger isn’t necessarily worth $600,000. It might be valued at $550,000 because the market doesn’t value extra space at a 1:1 ratio.
What This Means for Agents and Owners: If you’re helping price a home or evaluating renovations, remember that size matters—but how much it matters depends on the local market. Simply adding square footage doesn’t guarantee an equal return in appraised value.
Evaluating Property Condition
Condition is another critical element. Appraisers look at the property’s overall upkeep, including both cosmetic finishes and major systems like roofing, HVAC, plumbing, and electrical. A home in excellent condition with modern updates typically earns a higher market value than a similar home in poor condition.
For instance, energy-efficient windows, a new roof, or a remodeled kitchen can positively influence value—but only if those features align with what buyers in that market are paying more for.
What This Means for Agents and Owners: Updates don’t automatically increase value. Agents should be prepared to discuss condition with sellers in relation to comparable homes in the neighborhood. Homeowners should know that quality upgrades can improve marketability, but appraisers base adjustments on what similar homes have actually sold for.
The Combined Impact of Size and Condition
Appraisers evaluate size and condition together, not in isolation. For example, a large home in poor condition may appraise lower than a smaller home in excellent shape. The context of the local market and buyer demand is key.
Appraisers use techniques like paired sales analysis—comparing similar homes with one key difference—to isolate the value of features like square footage or renovated kitchens. Adjustments aren’t based on set formulas but rather on what the market data supports.
What This Means for Agents and Owners: Agents can better advise clients by understanding that appraisers make value adjustments based on how buyers perceive features in the current market. Homeowners planning upgrades should focus on improvements that are both functional and consistent with neighborhood expectations.
Conclusion
Understanding how appraisers evaluate home size and condition helps demystify a process that can feel opaque. For agents, this knowledge supports better pricing strategies and stronger transactions. For homeowners, it means making informed renovation decisions and having realistic expectations.
Keep in mind: every appraisal is unique, and no single feature guarantees a specific value. The market—not opinion—drives valuation.
Disclaimer: The insights shared in this article are meant to help agents and homeowners understand general appraisal concepts. Only a licensed or certified appraiser can develop or communicate an opinion of value in compliance with the Uniform Standards of Professional Appraisal Practice (USPAP).
by Conrad Meertins | Jan 20, 2025 | Valuation
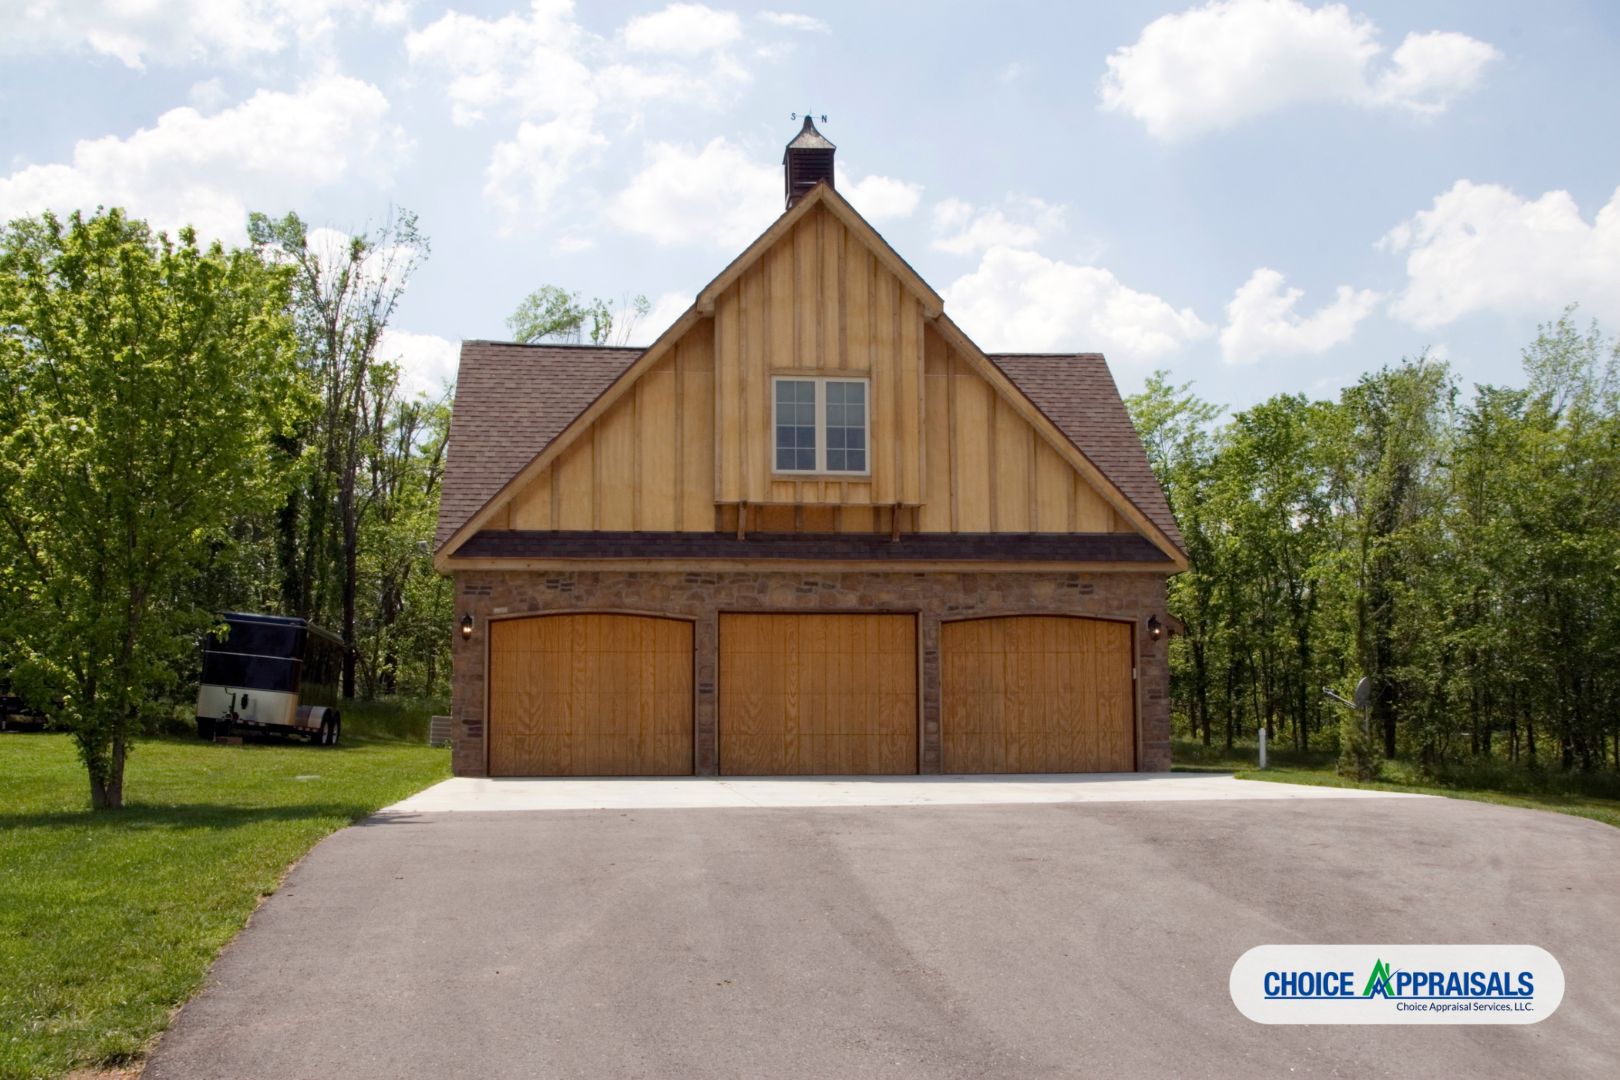
My first experience with an ADU was about a decade ago in Old Louisville. It was a four-story single-family residence (a beautiful brownstone). Just as I thought I had finished the appraisal, the owner asked, “Would you like to see the carriage house?”
I didn’t know there was more to see, but I confidently said, “Of course!” I was looking forward to it, not realizing at the time how ADUs would eventually become a significant trend in real estate.
As a Louisville appraiser, I’ve witnessed firsthand how Accessory Dwelling Units (ADUs) are reshaping our local real estate market. From the historic carriage houses in Old Louisville to newly constructed garden suites in St. Matthews, these versatile spaces are becoming increasingly valuable additions to Kentucky properties.
Let’s explore how ADUs impact market value, both positively and negatively, and what homeowners and buyers need to know about Fannie Mae’s guidelines.
The Upside: Positive Impacts of ADUs on Market Value

1. Increased Property Value in Our Market
Here in Louisville, where housing demand continues to grow, particularly in areas like the Highlands and Crescent Hill, ADUs often significantly increase a property’s value. The charm of our historic neighborhoods makes these additions especially appealing when they complement the architectural character of the main residence.
2. Rental Income Potential in Derby City
With the Kentucky Derby, Louisville’s growing tourism industry, and our expanding medical district, ADUs offer unique rental opportunities. From short-term rentals during major events to long-term leases for medical residents and students, ADUs can provide substantial income streams that help offset mortgage costs or generate additional cash flow.
3. Enhanced Market Appeal in Our Community
Louisville’s multi-generational families and young professionals are increasingly seeking properties with ADUs. Whether it’s housing aging parents in Cherokee Gardens or creating a home office in Clifton, these spaces offer the flexibility and versatility that our local market demands.
4. Flexibility in Use
ADUs can adapt to the changing needs of homeowners. Today, they might serve as a rental unit or guest house; tomorrow, they could be a home office, a space for aging relatives, or even a short-term rental during Derby week.
Challenges to Consider: The Downsides of ADUs
While ADUs offer incredible benefits, there are challenges to keep in mind:
1. High Construction Costs
Building an ADU can be a significant upfront investment, ranging from $100,000 to over $400,000 depending on size, design, and location.
2. Zoning and Regulatory Hurdles
Local zoning laws and permitting requirements can be complicated. Noncompliant or illegal ADUs may impact insurance claims, property marketability, or financing options.
3. Increased Property Taxes
Adding an ADU typically increases a property’s assessed value, which means higher property taxes.
4. Maintenance and Management
For those renting out their ADU, property management and maintenance become ongoing responsibilities.
5. Type of ADU Impacts Value Differently
- Detached ADUs generally add the most value.
- Attached ADUs come next.
- Internal ADUs (like basement apartments) add the least value but can still be significant depending on the market.
What Does Fannie Mae Say About ADUs?
As a key player in the mortgage market, Fannie Mae provides specific guidelines for properties with ADUs:
- Appraisal Requirements: Appraisers must evaluate how the ADU contributes to market value by analyzing comparable sales or, if none are available, using a cost-based approach.
- Gross Living Area (GLA): ADUs are appraised separately from the main dwelling unless they are within it and have interior access.
- Legal Compliance: ADUs must meet local zoning laws and regulations to be included in the property’s valuation.
- Financing and Underwriting: Lenders must follow specific loan-to-value (LTV) and debt-to-income (DTI) guidelines while factoring in potential rental income from the ADU.
Real-Life Insights: ADUs in Louisville
My most recent experience with an ADU involved a proposed construction project—a $1.3 million build featuring a 3,500-square-foot main residence with an attached garage and a 1,500-square-foot ADU on the other side of the garage.
The design was not only stunning but also supported by the local market, demonstrating a positive correlation between construction costs and property value in this case.
Looking Forward: What ADUs Mean for Louisville
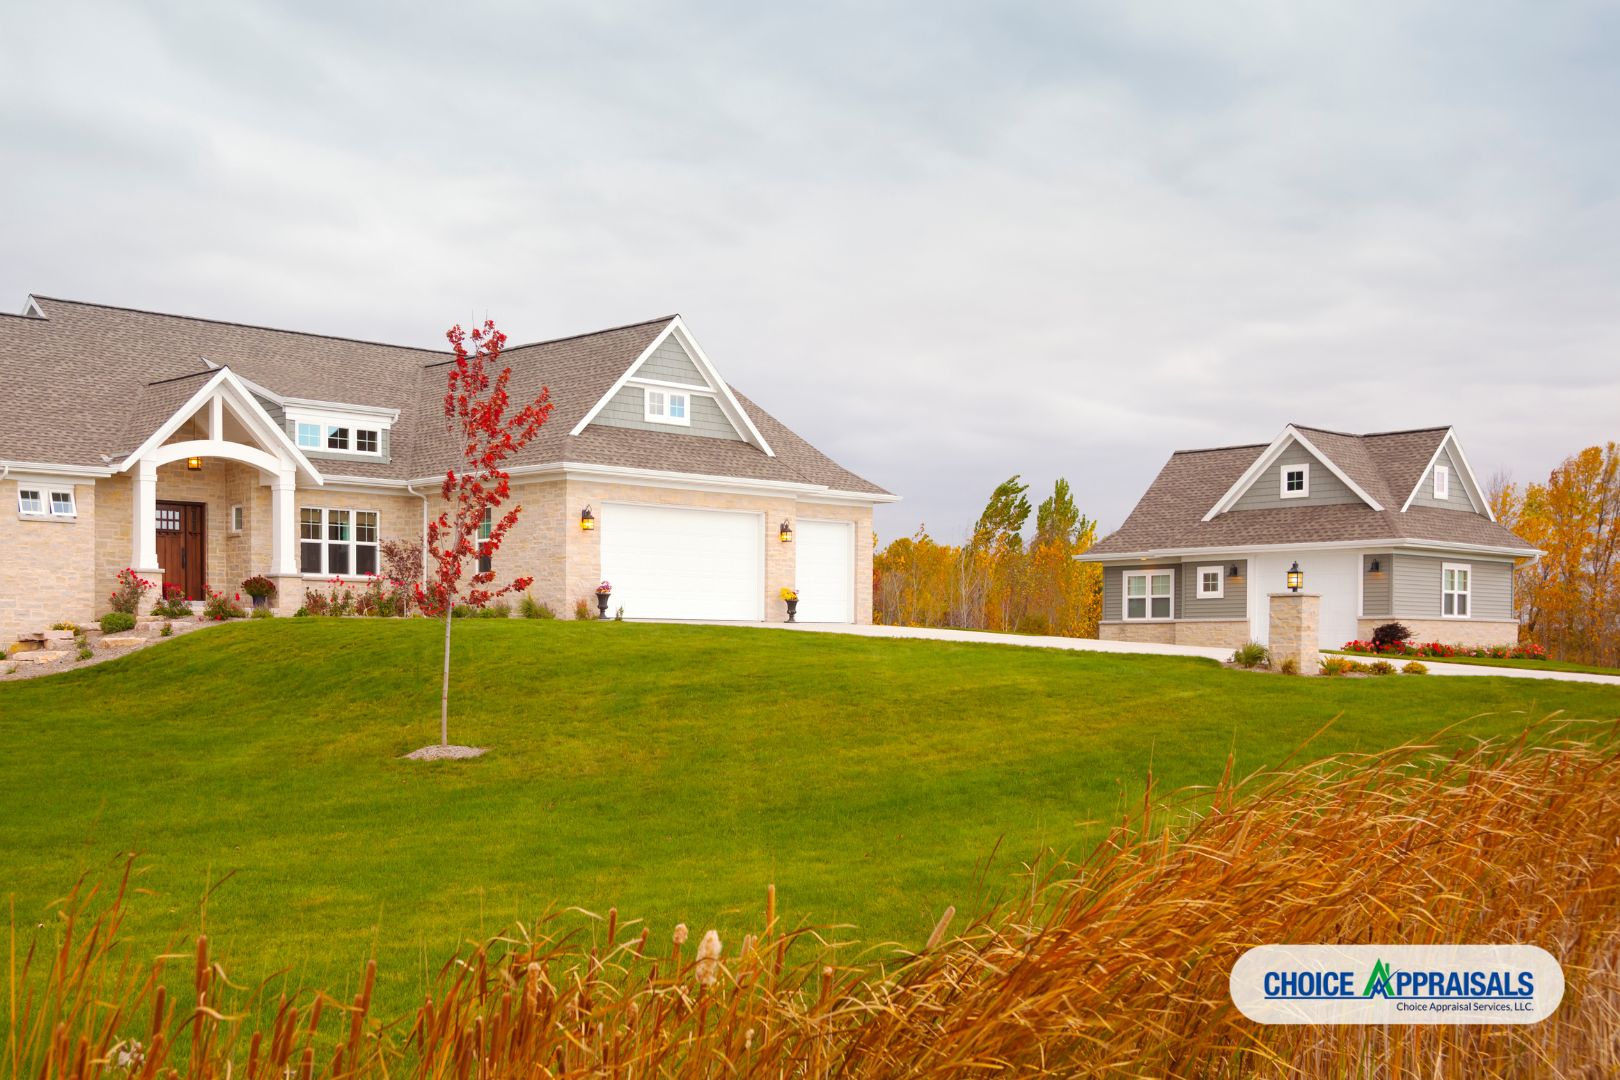
As Louisville continues to grow and evolve, ADUs represent a significant opportunity for property owners. Whether you’re in the Highlands, Butchertown, or the expanding East End, understanding how these units impact property values is crucial for making informed real estate decisions.
Adding an ADU can increase property value, generate income, and provide flexibility, but it also requires careful planning, compliance with local regulations, and a clear understanding of market trends.
Fannie Mae’s guidelines play a vital role in shaping how ADUs are appraised and financed, so it’s important to factor these into your decision-making process.
If you’re considering adding an ADU to your property—or buying a home with one—consulting with a professional appraiser who understands the local market can make all the difference.
Need professional guidance on ADU appraisal in Louisville? Contact me for a thorough valuation of your property’s potential!