by Conrad Meertins | Jun 10, 2026 | Valuation

Imagine two professionals walking through the same house in the same week. One is on his knees in the crawlspace with a flashlight, testing whether the sump pump kicks on. The other is in the living room with a tape measure and a clipboard, photographing the layout and jotting notes about the floor plan. To the homeowner watching from the kitchen, they look like they are doing the same job. They aren’t. They aren’t even answering the same question.
If you have ever felt fuzzy on where the home inspection ends and the appraisal begins, you are in good company. Buyers, sellers, and even seasoned agents mix these two up all the time. Let me walk you through the difference the way I would explain it to someone sitting across my desk, because understanding it will save you confusion at exactly the moment a transaction gets stressful.
Two different questions
Here is the cleanest way to keep them straight.
A home inspection answers the question: what condition is this house in? An inspector is looking at how the components of the home are functioning, including the roof, the furnace, the wiring, the plumbing, and the foundation, and flagging what is worn, broken, or unsafe.
A home appraisal answers a different question: what is this property worth, and how was that conclusion supported? An appraiser develops an opinion of value based on the market, drawing on comparable sales, the characteristics of the property, and the conditions of the local area, then documents the reasoning in a report.
Condition versus value. That single distinction clears up most of the confusion. The inspector studies the house itself. The appraiser studies how the house sits within its market.
What a home inspection is

A home inspection is a detailed, top-to-bottom examination of the physical condition of a property, usually performed by a licensed home inspector after a purchase contract is signed. The buyer typically orders and pays for it, and it is done for the buyer’s benefit.
The inspector’s job is to find and describe problems. Think of a water heater near the end of its life, a roof with a few years left, a cracked heat exchanger, or evidence of past moisture in the basement. The deliverable is an inspection report, often dozens of pages with photographs, that helps the buyer understand what they are walking into and what may need attention.
What an inspection is not is a statement of what the home is worth. An inspector will not tell you the market value, and a clean inspection does not mean a property will appraise a certain way. They are simply different lenses.
What a home appraisal is

A home appraisal is an independent, impartial opinion of a property’s value, developed by a state-licensed or certified appraiser. In a typical purchase with financing, the lender orders the appraisal, not the buyer or the seller, because the lender needs an objective third party to support the amount being loaned against the property.
That word *impartial* is the heart of it. An appraiser does not work for the buyer or the seller, and is not an advocate for either side. The appraiser’s obligation is to the analysis: to gather relevant data, apply recognized methods, and report a credible, supportable conclusion. Appraisers are bound by the Uniform Standards of Professional Appraisal Practice (USPAP), a set of ethics and performance standards that exist precisely to keep that objectivity intact.
When I measure a home and walk it, I am noting characteristics that influence value, such as size, layout, quality, condition, and how it compares to what else has sold nearby. I observe condition, but through the lens of how the market would respond to it, not as a punch list of repairs. That is a meaningfully different task than an inspection.
Where people get tripped up

A few mix-ups come up again and again, so let me name them directly.
The first one: “the appraiser will tell me everything that is wrong with the house.” That is not their role. An appraiser observes condition as it relates to value and notes items that are readily apparent, but an appraisal is not a substitute for an inspection. If you want a thorough accounting of the home’s working parts, that is what an inspection is for.
The second: “if the inspection looks good, the appraisal will too.” These measure different things. A home can be in excellent condition and still be analyzed against its market like any other property. A clean bill of health from an inspector is about condition, not value.
The third: “they are both just the bank’s box to check.” Each serves a distinct purpose. The inspection protects the buyer’s understanding of the home. The appraisal gives the lender an independent, supported analysis. Different audiences, different questions.
Putting it to work

So how do you use this, practically?
If you are a buyer or seller, remember that these two reports answer different questions, and you generally want both perspectives in a transaction. One helps you understand the home’s condition. The other provides an independent analysis of value for the lender. Do not expect either to do the other’s job.
If you are a real estate agent, this is a place where you can add real value for your clients. When you can explain clearly why the inspection and the appraisal are separate, and set expectations early, you reduce the surprise and friction that tend to surface late in a deal. Clients remember the professional who made the process make sense.
And if you ever find yourself unsure which report addresses your question, come back to the simple test. Am I asking about the condition of the house, or about its value? The answer tells you which professional you need.
A final thought
I have spent years on both sides of the front door, measuring, analyzing, and explaining how value gets supported. What I have learned is that most of the friction in a real estate transaction comes not from the numbers themselves, but from misunderstandings about who does what and why. The appraisal and the inspection are not competitors, and they are not interchangeable. They are two different tools, built to answer two different questions, and a transaction tends to go more smoothly when everyone understands which is which.
The more you understand each professional’s role, the better equipped you are to ask the right questions. And there is always a bit more to learn about how this all fits together.
by Conrad Meertins | Jan 20, 2025 | Valuation
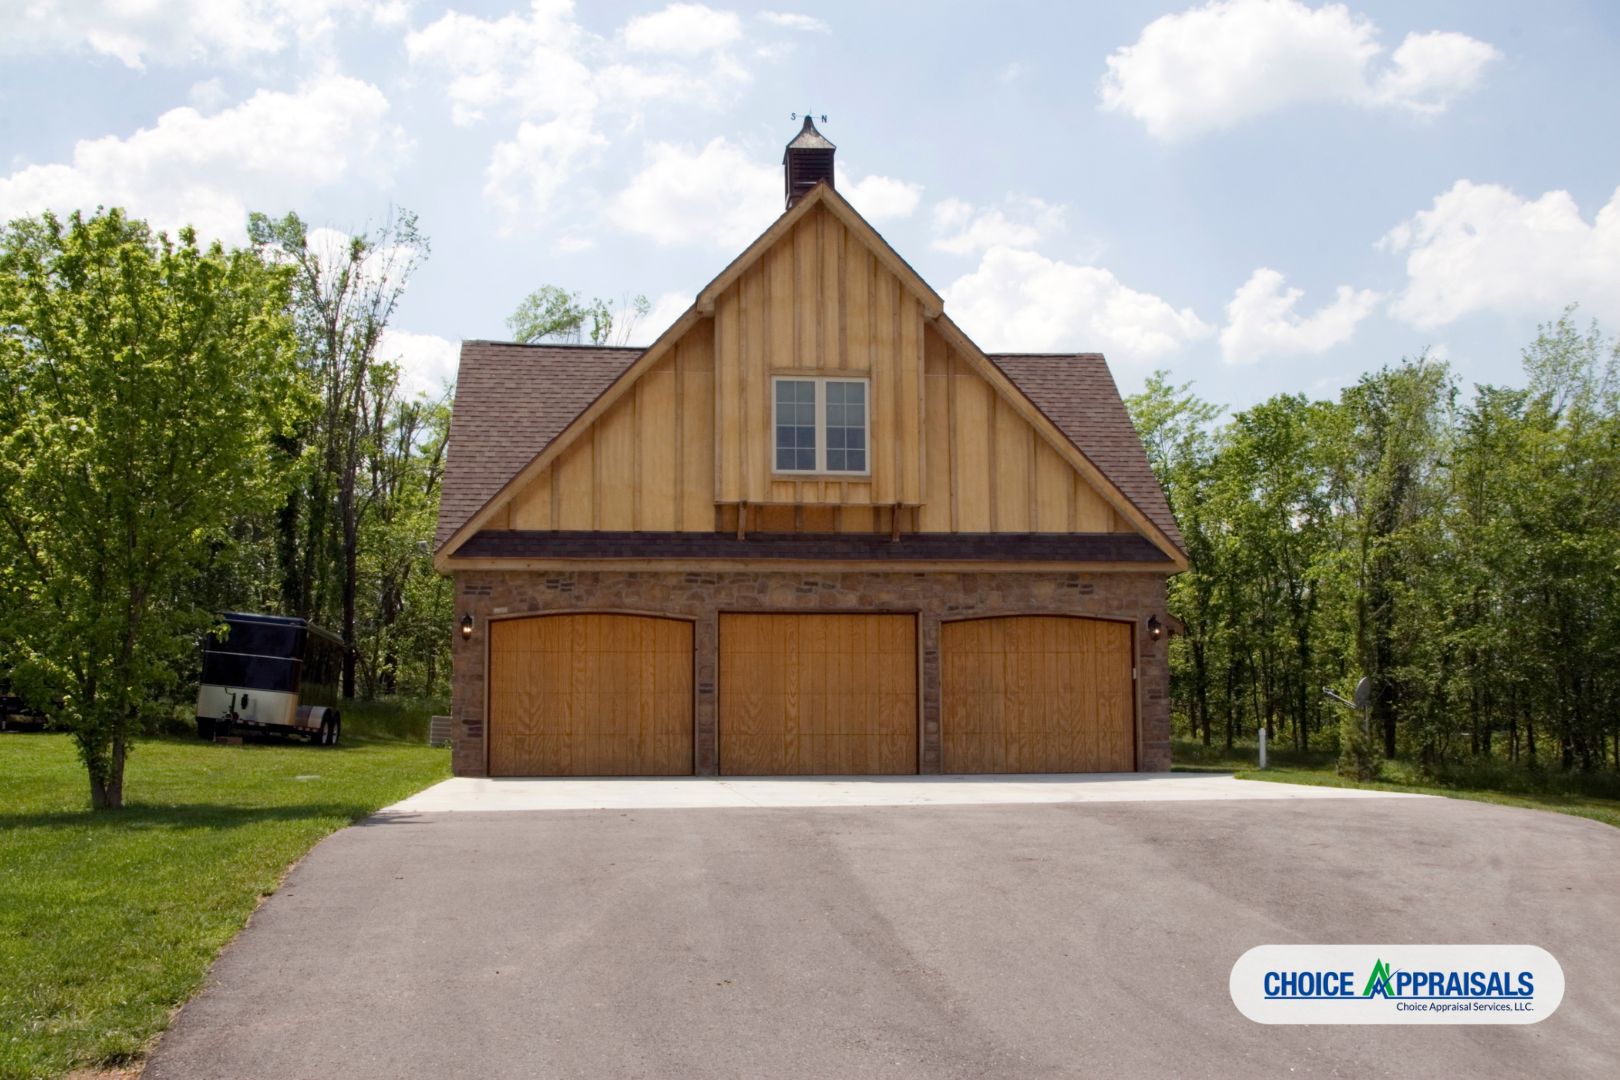
My first experience with an ADU was about a decade ago in Old Louisville. It was a four-story single-family residence (a beautiful brownstone). Just as I thought I had finished the appraisal, the owner asked, “Would you like to see the carriage house?”
I didn’t know there was more to see, but I confidently said, “Of course!” I was looking forward to it, not realizing at the time how ADUs would eventually become a significant trend in real estate.
As a Louisville appraiser, I’ve witnessed firsthand how Accessory Dwelling Units (ADUs) are reshaping our local real estate market. From the historic carriage houses in Old Louisville to newly constructed garden suites in St. Matthews, these versatile spaces are becoming increasingly valuable additions to Kentucky properties.
Let’s explore how ADUs impact market value, both positively and negatively, and what homeowners and buyers need to know about Fannie Mae’s guidelines.
The Upside: Positive Impacts of ADUs on Market Value

1. Increased Property Value in Our Market
Here in Louisville, where housing demand continues to grow, particularly in areas like the Highlands and Crescent Hill, ADUs often significantly increase a property’s value. The charm of our historic neighborhoods makes these additions especially appealing when they complement the architectural character of the main residence.
2. Rental Income Potential in Derby City
With the Kentucky Derby, Louisville’s growing tourism industry, and our expanding medical district, ADUs offer unique rental opportunities. From short-term rentals during major events to long-term leases for medical residents and students, ADUs can provide substantial income streams that help offset mortgage costs or generate additional cash flow.
3. Enhanced Market Appeal in Our Community
Louisville’s multi-generational families and young professionals are increasingly seeking properties with ADUs. Whether it’s housing aging parents in Cherokee Gardens or creating a home office in Clifton, these spaces offer the flexibility and versatility that our local market demands.
4. Flexibility in Use
ADUs can adapt to the changing needs of homeowners. Today, they might serve as a rental unit or guest house; tomorrow, they could be a home office, a space for aging relatives, or even a short-term rental during Derby week.
Challenges to Consider: The Downsides of ADUs
While ADUs offer incredible benefits, there are challenges to keep in mind:
1. High Construction Costs
Building an ADU can be a significant upfront investment, ranging from $100,000 to over $400,000 depending on size, design, and location.
2. Zoning and Regulatory Hurdles
Local zoning laws and permitting requirements can be complicated. Noncompliant or illegal ADUs may impact insurance claims, property marketability, or financing options.
3. Increased Property Taxes
Adding an ADU typically increases a property’s assessed value, which means higher property taxes.
4. Maintenance and Management
For those renting out their ADU, property management and maintenance become ongoing responsibilities.
5. Type of ADU Impacts Value Differently
- Detached ADUs generally add the most value.
- Attached ADUs come next.
- Internal ADUs (like basement apartments) add the least value but can still be significant depending on the market.
What Does Fannie Mae Say About ADUs?
As a key player in the mortgage market, Fannie Mae provides specific guidelines for properties with ADUs:
- Appraisal Requirements: Appraisers must evaluate how the ADU contributes to market value by analyzing comparable sales or, if none are available, using a cost-based approach.
- Gross Living Area (GLA): ADUs are appraised separately from the main dwelling unless they are within it and have interior access.
- Legal Compliance: ADUs must meet local zoning laws and regulations to be included in the property’s valuation.
- Financing and Underwriting: Lenders must follow specific loan-to-value (LTV) and debt-to-income (DTI) guidelines while factoring in potential rental income from the ADU.
Real-Life Insights: ADUs in Louisville
My most recent experience with an ADU involved a proposed construction project—a $1.3 million build featuring a 3,500-square-foot main residence with an attached garage and a 1,500-square-foot ADU on the other side of the garage.
The design was not only stunning but also supported by the local market, demonstrating a positive correlation between construction costs and property value in this case.
Looking Forward: What ADUs Mean for Louisville
As Louisville continues to grow and evolve, ADUs represent a significant opportunity for property owners. Whether you’re in the Highlands, Butchertown, or the expanding East End, understanding how these units impact property values is crucial for making informed real estate decisions.
Adding an ADU can increase property value, generate income, and provide flexibility, but it also requires careful planning, compliance with local regulations, and a clear understanding of market trends.
Fannie Mae’s guidelines play a vital role in shaping how ADUs are appraised and financed, so it’s important to factor these into your decision-making process.
If you’re considering adding an ADU to your property—or buying a home with one—consulting with a professional appraiser who understands the local market can make all the difference.
Need professional guidance on ADU appraisal in Louisville? Contact me for a thorough valuation of your property’s potential!
by Conrad Meertins | Jan 13, 2025 | Uncategorized
In the world of real estate, few topics generate more discussion and debate than property appraisals. As a crucial component of nearly every real estate transaction, understanding how appraisers actually use comparables (or “comps”) can make the difference between a smooth closing and a deal-breaking surprise. Let’s pull back the curtain on this often misunderstood process.
Beyond the “Closest House” Myth
One of the most persistent myths in real estate is that the house down the street is automatically the best comparable. While proximity matters, it’s just one piece of a complex puzzle. Professional appraisers consider numerous factors when selecting comparables:
Market timing is crucial – a sale from six months ago might be less relevant than a similar property that sold last month in a neighboring community, especially in rapidly changing markets. The goal is to capture the most accurate snapshot of current market conditions, not simply find the closest properties.
Consider this: A colonial-style home with premium finishes might have more in common with a similar property half a mile away than with the ranch-style house next door, even if they share the same square footage. Professional appraisers understand these nuances and select comparables that truly reflect the subject property’s characteristics.
The Science Behind Adjustments
Contrary to popular belief, appraisal adjustments aren’t arbitrary numbers pulled from thin air. They’re based on detailed market analysis and documented evidence. Here’s how it really works:
Appraisers use paired sales analysis to isolate the value of specific features. By comparing similar homes where one has a particular feature (like a finished basement) and one doesn’t, they can determine the market’s actual response to that feature. This method provides concrete evidence for adjustments rather than relying on construction costs or personal opinion.
Let’s look at some real market data from our downtown area that demonstrates how adjustments are determined:
Real Market Data: Bedroom Count Impact
Recent market analysis reveals clear value differences based on bedroom count and their corresponding median sales price (keep in mind this data for one specific market area as of this month:
- 2 bedrooms: $116,500
- 3 bedrooms: $151,000
- 4 bedrooms: $169,000
This data tells us that the market values the difference between a 2-bedroom and 3-bedroom home at approximately $34,500, while the jump from 3 to 4 bedrooms adds about $18,000 in value. When appraisers make bedroom count adjustments, they use this type of market-derived data rather than arbitrary figures.
Real Market Data: Basement Configuration
The market also shows clear preferences for different basement types:
- No basement: $115,000
- Interior access only: $146,300
- Outside entry: $160,000
This data indicates that adding a basement with outside entry adds about $45,000 to a home’s value compared to no basement, while an interior-access-only basement adds approximately $31,300. These are the kinds of concrete market differences that inform adjustment decisions.
Why Your Renovation Might Not “Add Up”

One of the most challenging conversations in real estate is explaining why a $50,000 kitchen renovation might not result in a $50,000 increase in appraised value. The reason lies in how markets actually respond to improvements:
Markets often recognize value differently than construction costs. While a high-end kitchen renovation might cost $50,000, if similar homes in the area typically sell for only $25,000 more with updated kitchens, that’s what the market is willing to pay. Appraisers must reflect this market reality in their adjustments, regardless of actual improvement costs.
The Role of Market Conditions
Time adjustments are perhaps the most misunderstood aspect of the appraisal process. In rapidly changing markets, even sales from three months ago might need significant adjustments to reflect current conditions. These adjustments are based on documented market trends, not guesswork.
For example, if market analysis shows home values in an area have appreciated by 1% per month, a comparable sale from four months ago would need a 4% upward adjustment to reflect current market conditions. This systematic approach ensures that older sales remain relevant while accounting for market changes.
Professional Judgment in Context
While appraisal adjustments are data-driven, professional judgment still plays a vital role. The key is understanding where and how this judgment is applied:
Appraisers must weigh competing factors, such as whether to use an older sale that’s very similar to the subject property or a more recent sale that requires larger adjustments. These decisions are guided by professional standards and market evidence, not personal preference.
Working Together for Better Outcomes
For real estate professionals and homeowners alike, understanding the appraisal adjustment process leads to better outcomes. Here’s how you can help:
- Maintain detailed records of improvements, including dates and costs
- Document any unique features or recent updates that might not be visible during inspection
- Provide information about recent changes in the neighborhood that might affect value
- Be prepared to share information about any previous offers or market exposure
The Bottom Line
The appraisal adjustment process is far more rigorous and market-based than many realize. While it may sometimes deliver unexpected results, understanding how comparables are really used can help all parties navigate the process more effectively.
Remember: The goal of an appraisal is not to hit a predetermined number but to provide an objective opinion of value based on market evidence. When all parties understand this fundamental truth, we can work together more effectively to facilitate successful real estate transactions.
by Conrad Meertins | Dec 16, 2024 | Uncategorized
You’ve heard it before: the home is where the heart is. But it’s also where a good chunk of your financial investment lies. Whether it’s your forever home or a stepping stone to your dream abode, you’ve probably considered some form of home renovation.
Maybe you’re looking to add a touch of comfort, or perhaps you’re aiming to increase your property’s market value. Either way, it’s crucial to understand the dynamics between home renovations and market value.
Think of your home as an artist’s canvas. Each stroke of renovation you add can either enhance the masterpiece, increasing its worth, or muddy the image, making it less attractive to potential buyers.
Not all renovations are created equal, and some can even detract from your home’s value. So, how do you navigate this tricky terrain?
That’s where I, your appraiser friend, come in. This article aims to be your trusty compass, guiding you through the world of home renovations and their impact on market value.
We’ll dive into the correlation between the two, explore the types of renovations that can boost your home’s worth, and even discuss some improvements that might not add the value you’d expect.
Understanding the relationship between renovations and market value is not just about making savvy financial decisions. It’s about creating a space that’s both personally fulfilling and economically smart. So, grab your hard hat and let’s get started!
The Relationship Between Home Renovations and Market Value
Imagine this: you’ve decided to renovate your home, perhaps you’ve upgraded your kitchen with sleek granite countertops, installed a luxurious whirlpool bathtub in your bathroom, or maybe you’ve transformed your backyard into an inviting oasis with a pool and a deck.
You’ve invested time, effort, and a good chunk of change into these projects, but have you ever paused to consider how these changes are affecting your home’s market value?
The relationship between home renovations and market value is a fascinating one. It’s a bit like cooking a gourmet meal; the right ingredients, when combined thoughtfully, can create a dish that’s worth more than the sum of its parts. Similarly, strategic renovations can significantly increase your home’s market value.
But let’s be clear: not all renovations are created equal. While some can boost your home’s value considerably, others might not have the same effect. It’s a bit of a balancing act, knowing which renovations will reap the most rewards.
This is why understanding the correlation between home renovations and market value is crucial. It’s not just about making your home look better; it’s about making strategic improvements that will increase its worth in the eyes of potential buyers.
It’s like playing chess; every move you make should be deliberate, with an eye on the endgame. Renovating willy-nilly can lead to a mishmash of styles and improvements that don’t necessarily add value.
But when you renovate strategically, you’re investing in your home’s future, and that can pay off big time when it’s time to sell.
So, the next time you’re considering a home renovation project, don’t just think about the immediate benefits. Think about the potential impact on your home’s market value. Because in the grand scheme of things, that’s where the real payoff lies.
Types of Renovations That Improve Market Value

Now that we’ve established the connection between home renovations and market value, let’s dive a little deeper. The key lies in identifying those improvements that are likely to appeal to a broad range of potential buyers.
First on the list is the heart of any home – the kitchen. A well-executed kitchen remodel can significantly increase the value of your home. Think about it: the kitchen is where families gather, meals are prepared, and memories are made.
It’s not just about having the latest appliances or the most fashionable countertops. It’s about creating a functional, welcoming space that can adapt to a family’s evolving needs.
Bathroom upgrades are another smart investment. Modern buyers are looking for bathrooms that offer a sense of luxury and relaxation.
This doesn’t necessarily mean you need to install a top-of-the-line whirlpool tub or a rainfall showerhead (although those can be nice!). Sometimes, simple updates like new fixtures, fresh paint, or improved lighting can make a world of difference.
Don’t forget about the outdoors. In today’s market, outdoor living spaces are more valuable than ever. This could mean adding a deck or patio, sprucing up your landscaping, or even installing a pool if it fits with the overall vibe of your neighborhood (i.e. you’re in Florida and every home but yours has a pool).
Lastly, consider the overall flow and functionality of your home. Are there walls that could be knocked down to create an open-concept living area? Could the attic be transformed into a cozy loft? These types of renovations can not only make your home more enjoyable to live in, but also more appealing to potential buyers.
The bottom line? Renovations that improve the functionality, appeal, and overall quality of your home are likely to increase its market value. But remember, every home and every market is unique.
What works in one area might not work in another. That’s why it’s always a good idea to consult with a real estate appraiser before making any major renovation decisions. They can provide valuable insight into what buyers in your area are looking for and help you make the most of your renovation budget.
Tips for Successful Home Renovations
So, you’re ready to jump into the home renovation bandwagon? That’s great! But before you do, let’s sit down and talk about how to make your home renovations work for you, not just in terms of aesthetics, but more importantly, in improving your home’s market value.
First off, the importance of planning and budgeting cannot be overstated. Imagine walking into a grocery store without a shopping list. You might end up with a cart full of items you don’t need, right? The same principle applies to home renovations.
Without a solid plan, you risk spending money on renovations that don’t significantly increase your home’s market value. So, take the time to identify which areas of your home need improvement and how much you’re willing to spend on each project.
Next, let’s talk about quality. You might be tempted to cut corners to save money, but remember, you get what you pay for. High-quality materials and workmanship not only add value to your home but also save you from potential headaches down the line.
Think about it: if a buyer walks into your newly renovated kitchen and sees that the cabinets are poorly installed or the tiles are chipped, do you think they’d be willing to pay top dollar for your home? Probably not.
Now, you might be thinking, “But I’m not a renovation expert. How do I ensure quality?” That’s where hiring professionals comes in. Yes, it might cost more upfront, but having experts handle your renovations can ensure that the work is done right the first time. Plus, they can offer valuable insights into what renovations can boost your home’s market value.
Lastly, remember that successful home renovations aren’t just about making your home look pretty. They’re about making strategic improvements that can increase your home’s market value.
So, before you start knocking down walls or installing a new bathtub, ask yourself, “Will this renovation appeal to potential buyers? Will it improve the functionality and overall appeal of my home?” If the answer is yes, then you’re on the right track.
In the end, successful home renovations are all about balance. It’s about balancing your personal preferences with what potential buyers might want, balancing aesthetics with functionality, and balancing your budget with the potential return on investment.
So, take the time to plan, prioritize quality, hire professionals, and make strategic improvements. Your home—and your wallet—will thank you.
Renovations That May Not Add Value
So, you’ve got a wild idea for a renovation. Maybe you’re thinking of installing an indoor rock climbing wall in the living room or perhaps you’re contemplating transforming your basement into a full-scale replica of the Starship Enterprise.
While these may be thrilling personal projects, it’s important to remember that not all renovations add value to your home. In fact, some could even decrease your property’s market value. Let’s delve into this.
Firstly, overly personalized renovations can be a double-edged sword. On one hand, they make your home uniquely yours, a space that reflects your personality and passions. On the other hand, these renovations may not appeal to potential buyers who don’t share your particular interests.
A home with a custom-built aquarium in the master bedroom or a jungle-themed kitchen may be your dream come true, but for others, it might be a remodeling nightmare.
Secondly, luxury upgrades that exceed the neighborhood’s standard could also fail to add significant value. Imagine installing a top-of-the-line, professional-grade kitchen in a neighborhood of starter homes.
Sure, it’s a fantastic feature, but if it dramatically inflates your home’s price compared to other properties in the area, buyers might not bite. After all, they’re shopping in your neighborhood for a reason, and if your home’s price significantly exceeds the norm, it may be out of their budget.
Lastly, renovations that neglect the home’s overall harmony could potentially be detrimental. For instance, if you upgrade only one room while leaving the rest of the house outdated, it could create a jarring contrast that detracts from the overall appeal.
So, what’s the takeaway here? While it’s your home and you should absolutely love the space you’re in, it’s crucial to strike a balance. If you’re considering a renovation with the hopes of adding value to your home, think strategically.
Reflect on whether your project will have broad appeal, align with the standards of your neighborhood, and contribute to the overall coherence of your home.
How to Evaluate the Potential Return on Investment (ROI) for a Renovation
When it comes to home renovations, we’re not just talking about a fresh coat of paint or a new doorknob. We’re discussing investments, sometimes hefty ones, that can significantly affect your home’s market value. So, before you take the plunge, it’s crucial to evaluate the potential return on investment (ROI) for a renovation.
But how do you do that?
First, start by understanding the cost of the renovation. This isn’t just about the upfront expenses of materials and labor. Consider the ongoing maintenance costs, potential increased utility bills, and any other recurring costs that might be associated with the renovation.
Next, consider the potential increase in market value. This is where things get a bit tricky. You might be in love with the idea of a gold-plated bathtub, but will potential buyers feel the same way? Research the real estate market in your area and similar homes to get a sense of what renovations are adding value.
It’s also important to consider the timeline. If you’re planning to sell your home soon, you’ll want to focus on renovations that can provide a quick return on investment.
On the other hand, if you’re planning to stay in your home for several years, you might have more flexibility to consider renovations that will increase your enjoyment of the home, even if they don’t have an immediate impact on its market value.
Remember, not all renovations are created equal. A kitchen remodel might yield a high return on investment, while a luxury upgrade to your home theater might not. It’s all about finding the balance between what you want and what the market values.
Ultimately, evaluating the potential ROI for a renovation requires a mix of research, careful planning, and a bit of intuition. It’s not an exact science, but with some due diligence, you can make renovations that not only improve your quality of life but also boost your home’s market value.
The Impact of Renovations on Homeowner Happiness
Now, let’s take a detour from the financial aspect and delve into the emotional realm. After all, a home is not just a property; it’s a personal sanctuary, a space that should bring joy and satisfaction. So, how do renovations impact homeowner happiness?
According to the Home Remodeling Projects That Pay Back The Most In Happiness report, certain renovations significantly enhance homeowner happiness. For instance, a complete kitchen renovation, one of the most impactful upgrades you can make in terms of market value, also tops the list in terms of homeowner joy.
Imagine the satisfaction of cooking in a newly renovated kitchen with state-of-the-art appliances, custom cabinetry, and sleek countertops. It’s not just about the potential monetary return; it’s also about the personal enjoyment you derive from such improvements.
But here’s where it gets interesting: this happiness can indirectly affect market value. Think about it. A happy homeowner is likely to maintain their home better, addressing minor issues before they become major problems. This level of care and attention to detail can significantly enhance a home’s long-term market value.
Moreover, the emotional connection a homeowner feels towards their renovated home can translate into a more compelling sales pitch when it’s time to sell. Buyers don’t just purchase a property; they buy into a lifestyle, a vision of what their life could be in that home.
A homeowner who has derived genuine joy from their home can communicate that feeling more effectively to potential buyers, potentially commanding a higher selling price.
So, while it’s essential to consider the financial implications of renovations, don’t underestimate the power of homeowner happiness. The joy and satisfaction derived from improving your living space can have tangible benefits, both for your quality of life and your home’s market value.
Conclusion
As we draw this conversation to a close, it’s crucial to reflect on the core message: the importance of understanding how renovations can affect your home’s market value.
Just as a skilled chef knows that each ingredient can dramatically alter the taste of a dish, a savvy homeowner recognizes that every renovation – big or small – can significantly influence the market value of their home.
But let’s not forget – it’s not just about the money. While increasing your home’s market value is an undeniable benefit, the personal value derived from renovations shouldn’t be overlooked.
Whether it’s the joy of cooking in a newly remodeled kitchen or the peace of mind that comes with a reinforced roof, the happiness and satisfaction that these improvements bring are priceless.
Think of your home as a canvas. Each stroke of renovation not only adds to the aesthetic appeal but also contributes to the overall worth of the masterpiece. But remember, it’s not just about creating a showpiece for others to admire.
It’s about crafting a space that reflects your personality, caters to your needs, and yes, boosts your property’s market value.
So, whether you’re planning a minor tweak or a major overhaul, consider both the financial and personal value. Strategize, budget, and focus on quality.
After all, a well-planned renovation can be a win-win situation, enhancing both your quality of life and the thickness of your wallet.
Remember, the world of home renovations is vast and varied, and there’s always more to learn. So, keep exploring, keep improving, and most importantly, keep enjoying the process.
After all, home is not just a place, it’s a feeling. And every improvement you make is another step towards perfecting that feeling.
by Conrad Meertins | Dec 9, 2024 | Uncategorized
Whether you’re selling your home or refinancing your mortgage, an appraisal is a critical step in the process. Appraisers evaluate your property to determine its market value. However, certain issues, or “appraisal red flags,” can lower your home’s value. Let’s explore these red flags and how you can avoid them.
Introduction
Picture this: You’re ready to make a big move. You’ve got a buyer lined up for your home or you’re all set to refinance your mortgage. But there’s one crucial step left – the home appraisal. Enter the appraiser, the person who gets to decide the market value of your home. This individual walks through your property, eyes sharp, jotting down notes, assessing every nook and cranny.
Now, let’s talk about something called “appraisal red flags.” Think of these as the little gremlins that could potentially lower your home’s value in the eyes of the appraiser. It could be something as significant as a crack in the foundation or as subtle as outdated electrical systems.
This article will guide you through these red flags, helping you understand what they are and why it’s so important to be aware of them. Because, let’s face it, no one wants a lower appraisal than expected, right? So, let’s dive in and demystify these appraisal red flags.
Understanding Appraisal Red Flags
You’ve done everything you can think of to get your home ready to sell. Fresh paint on the walls, new fixtures in the bathroom, even a few strategic landscaping improvements to enhance curb appeal.
But when the appraiser arrives, they point out several issues that you hadn’t even considered. Suddenly, your home’s market value takes a hit. This is the power of “appraisal red flags.”
So, what exactly are these red flags? In the simplest terms, appraisal red flags are issues or conditions that can negatively impact the value of your home in the eyes of an appraiser. These can range from obvious physical problems, like a cracked foundation or outdated systems, to more subtle issues, like unpermitted renovations or even factors outside your home, like the gas station next door..
Now, you might be wondering: why should I care about these red flags? Well, in the world of real estate, knowledge is power. Being aware of potential appraisal red flags can help you anticipate issues before they become a problem, allowing you to address them proactively. Whether you’re a homeowner preparing for an appraisal or a buyer trying to understand the value of a potential investment, understanding these red flags can be a game-changer.
Think of it this way: each red flag is a conversation between you and the appraiser. They’re saying, “Hey, this could be a problem,” and you have the opportunity to respond, either by fixing the issue or by adjusting your expectations about your home’s value. So, let’s dive into these conversations and learn how to navigate them effectively.
Top 5 Appraisal Red Flags
Let’s dive into the nitty-gritty, shall we? Here are the top five red flags appraisers are on the lookout for when they swing by your property.
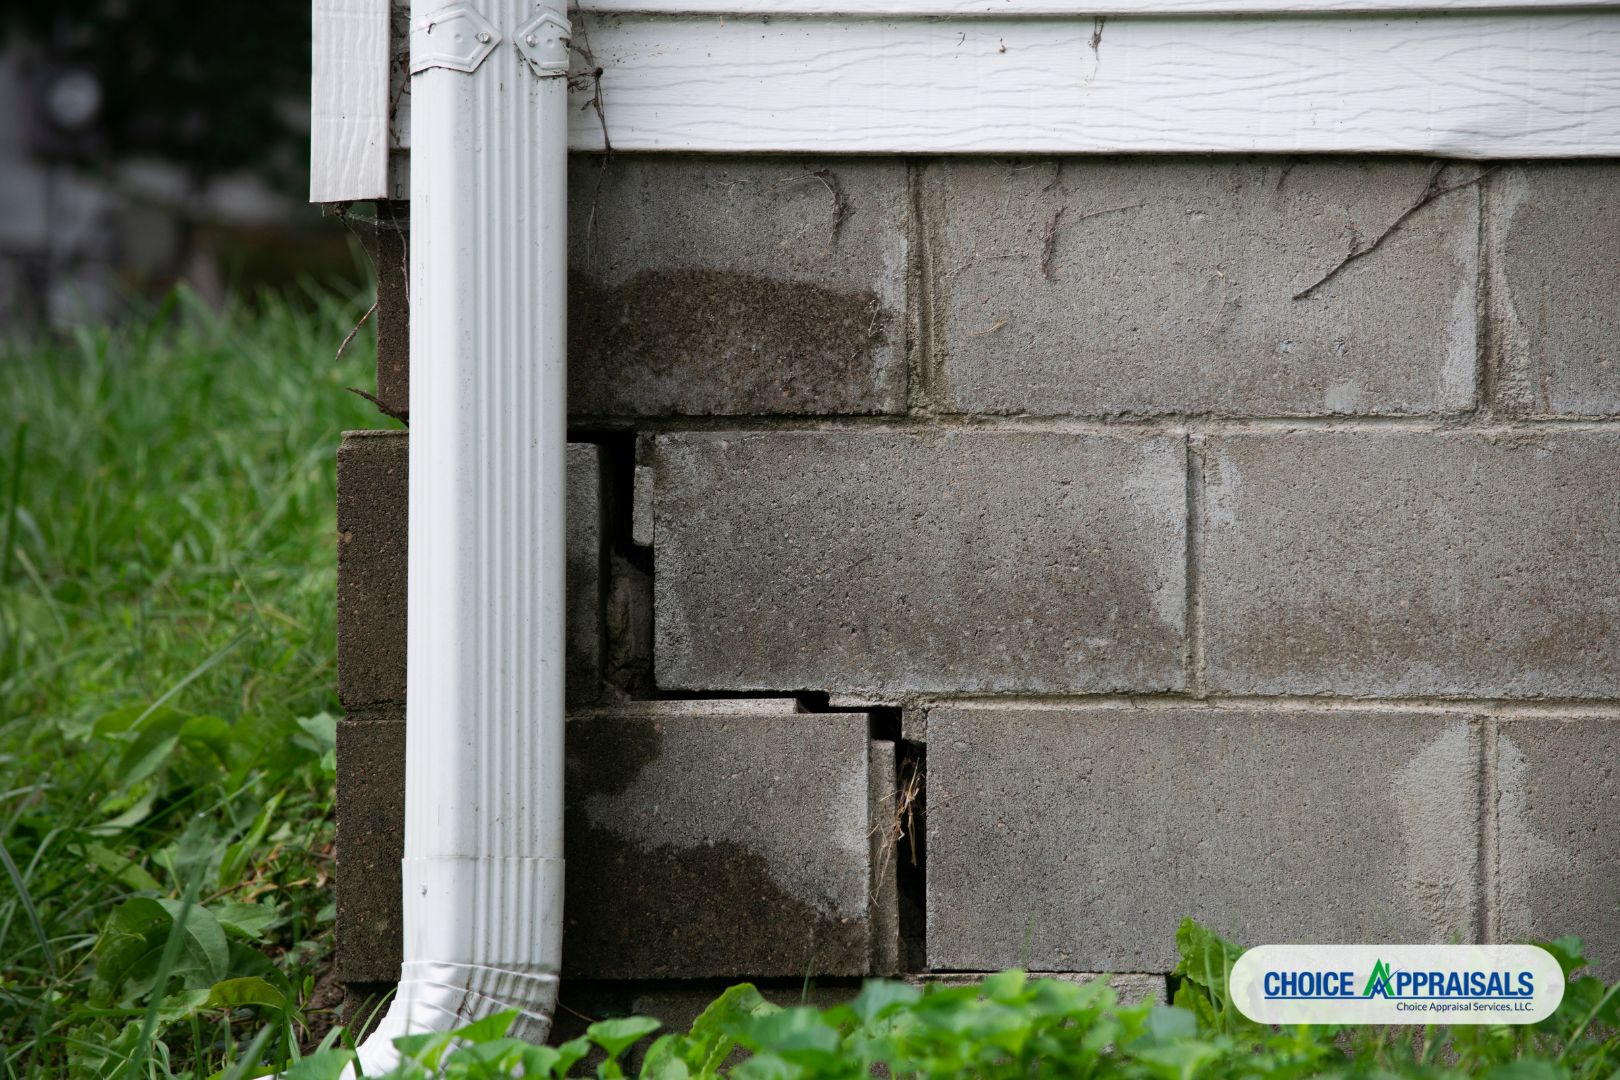
First up, Structural Issues. Think of your home as a human body, the structure is the skeleton that holds everything together. If there are cracks in the foundation or the roof looks like it’s seen better days, it’s like a broken bone or a bad back. It’s a serious problem. These types of issues can significantly knock down your home’s value because they’re costly to repair and can lead to other problems down the line. The key here is that if its observable to the appraiser that it’s something that he will likely notate in his or her report.
Next, we have Outdated Systems. If your home’s electrical, plumbing, or HVAC systems are older than the cast of Friends, you’ve got a problem. Appraisers know that outdated systems can be a ticking time bomb of expensive repairs. Plus, they’re not as efficient or safe as their modern counterparts. The appraiser is not a home inspector, but its easy to see corrosion on pipes, exposed electrical wires or leaking water heaters.
Thirdly, Poor Maintenance. You know that peeling paint you’ve been meaning to address or that leaky roof you’ve been ignoring? Yeah, appraisers notice that too. Signs of neglect like these are red flags because they suggest there might be other, potentially more serious issues lurking beneath the surface.
The fourth red flag is Unpermitted Additions. That DIY sunroom might seem like a selling point to you, but if it was done without the proper permits, it could be a liability. Unpermitted additions can lead to serious legal and safety issues, and appraisers may mention them in his report.
Finally, Neighborhood Factors. You might have the nicest house on the block, but if your block happens to be right next to a noisy highway, it’s going to hurt your appraisal. Appraisers take into account the market’s reaction to such influences when determining a home’s value.
In essence, appraisers are like home detectives, looking for clues that tell the true story of a property’s value. These five red flags are key indicators they use in their investigation. So, if you’re preparing for an appraisal, it’s wise to address these issues head-on. Don’t try to hide them or hope they’ll go unnoticed. Trust me, they won’t.
Tips to Avoid Appraisal Red Flags
So, you’ve got a good handle on what appraisers are on the lookout for – those pesky red flags that could potentially lower your home’s value. But what can you do about it? How can you make sure your home passes the appraisal with flying colors? Don’t worry, I’ve got your back. Let’s roll up our sleeves and dive into some practical tips that can help you sidestep these common appraisal pitfalls.
Firstly, take a good, hard look at your home. And I mean really look. Put yourself in the shoes of an appraiser. Are there any glaring issues that jump out at you? Cracked walls? Peeling paint? Outdated electrical systems? These are all things you’ll want to address before the appraiser’s visit.
Next, get your hands on a home inspection checklist. This can be a real lifesaver. It’ll guide you through each part of your home, helping you identify and fix potential red flags. And trust me, it’s a lot easier to fix these issues before the appraiser points them out.
Now, let’s talk about those unpermitted additions. You know, that fancy new deck you built last summer? If you didn’t get the proper permits for it, it could be a real thorn in your side during the appraisal. So, make sure you’ve got all your paperwork in order. If you’re missing any permits, now’s the time to get them.
Finally, remember that factors outside your home can also impact your appraisal. You might not be able to control the noise from the nearby highway, but you can make your home more appealing in other ways. A well-maintained garden, a new coat of paint, or even some attractive outdoor lighting can all help to boost your home’s curb appeal.
As Tom Horn, a seasoned appraiser from the Birmingham Appraisal Blog, wisely points out, “The best defense is a good offense.” By taking a proactive approach and addressing potential red flags before the appraisal, you’ll be in a much stronger position. So, don’t wait for the appraiser to knock on your door. Get ahead of the game and make sure your home is in tip-top shape.
Conclusion
So, there you have it, folks. We’ve taken a journey down the less-traveled road of home appraisal, shedding light on the elusive ‘red flags’ that can potentially play spoilsport in your home’s valuation game. Structural issues, outdated systems, poor maintenance, unpermitted additions, and neighborhood factors – they all play a pivotal role in determining the value of your home in the eyes of an appraiser.
Now, you might be thinking, “This all sounds pretty daunting, doesn’t it?” But here’s the kicker – it doesn’t have to be. As a homeowner, you hold the power to ensure a successful appraisal. It’s all about staying proactive, keeping your home in good shape, and addressing potential issues before they escalate into full-blown red flags. Remember, a well-maintained home is not just a pleasure to live in; it’s also a goldmine when it comes to appraisal.
So, go ahead. Take a good look around your home. Is there a crack in the foundation you’ve been ignoring? An outdated electrical system that’s due for an upgrade? Or maybe an unpermitted addition that needs to be legitimized? Tackle these issues head-on, and you’ll be well on your way to acing that appraisal.
In the end, it’s not just about getting a good appraisal. It’s about maintaining your home to the best of your ability, and ensuring it reflects the true value it holds. Because, let’s face it, your home is more than just a property – it’s a reflection of you. And you, my friend, are priceless.